Lower interest rates provide vital capital relief for Vietnamese businesses during year-end production surge

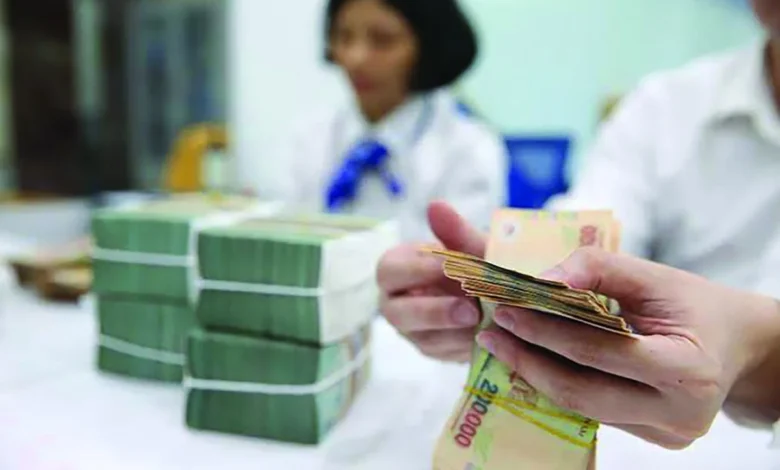
As the fiscal year draws to a close, Vietnamese enterprises are currently navigating a critical period defined by the convergence of peak production demands, the fulfillment of high-volume export contracts, and the rigorous planning cycles for the upcoming year. For many domestic manufacturers, this final quarter represents both an opportunity for revenue growth and a significant test of liquidity management. In a strategic move to sustain this economic momentum, the State Bank of Vietnam (SBV) has spearheaded a series of monetary policy adjustments that have effectively lowered lending rates, providing a much-needed reprieve for the business sector.
The Macroeconomic Context of Interest Rate Adjustments
The current economic landscape in Vietnam is characterized by a concerted effort to balance growth with monetary stability. Throughout the first ten months of 2026, the SBV has issued over ten key directives and circulars aimed at optimizing interest rate structures. These policy shifts have mandated that credit institutions proactively trim operational costs and reallocate internal profit margins to support lower borrowing rates for clients.
By the end of October 2026, the cumulative impact of these policies became evident. Statistical data indicates that deposit interest rates have declined by approximately 0.5% to 0.7% per annum, depending on the banking group. This downward shift in the cost of capital for banks has provided the necessary fiscal space to transfer benefits to the real economy. For businesses, this translates to tangible cost savings that directly influence production capacity and labor stability.
Real-World Impact: Case Studies in Manufacturing
The relief provided by these rate cuts is not merely theoretical; it is actively reshaping the financial operations of major industrial players. Two prominent examples illustrate the scale of this impact:
CTCP Tôn Thép Việt Pháp, a significant player in the steel sector, experienced a reduction of approximately 1.5 percentage points in borrowing costs toward the end of October, bringing their effective interest rate to roughly 6.1% per annum. According to Pham Thuy Hai, the company’s Financial Director, this adjustment has resulted in hundreds of millions of VND in monthly interest savings. The company has moved to immediately reinvest these savings into raw material procurement and the settlement of year-end bonuses, thereby stabilizing the workforce during a high-demand period.
Similarly, the Austdoor Group, which requires substantial revolving capital of 300 to 600 billion VND monthly, has reported significant benefits. With banks reducing lending rates by 0.5% to 1.5% per annum, Austdoor has managed to insulate itself from market volatility. Tran Phuong Linh, Head of the company’s Finance Department, noted that the reduced financial burden allows the group to maintain stable product pricing, which is a critical competitive advantage when managing year-end supply chain logistics and production planning for the next fiscal year.
The Mechanics of Monetary Support
The SBV’s strategy has evolved beyond simple rate mandates. On November 3, 2026, the central bank announced the implementation of foreign currency swap operations with a 6-month tenor for the Vietnamese Dong (VND). This represents a departure from the shorter, 1-2 week terms previously employed.
By extending the tenor of these swaps, the SBV has provided commercial banks with a more stable, medium-term source of VND liquidity. This intervention is designed to mitigate the pressure on short-term interbank interest rates. Nguyen The Minh, Director of Treasury at An Binh Securities (ABS), describes this as a highly timely measure. "The pressure on exchange rates has moderated, allowing the central bank to utilize swap tools to replenish VND liquidity in the banking system," Minh stated. "With more favorable swap costs, credit institutions are better positioned to meet liquidity demands without forcing upward pressure on lending rates."
Chronology of Policy Intervention (2026)
- Q1-Q2 2026: Initial focus on stabilizing inflation and managing credit growth in response to fluctuating global commodity prices.
- July 2026: The SBV signals a shift toward a more accommodative stance, urging banks to prioritize lending to production and export sectors.
- October 2026: Significant policy push; over ten circulars issued to enforce cost-cutting among lenders.
- Late October 2026: Data confirms a 0.2% – 0.5% decrease in interest rates for new loans. Over 20 commercial banks announce dedicated credit programs with rate reductions of 1.5% – 2%.
- November 3, 2026: Implementation of 6-month foreign currency swap operations to enhance systemic liquidity.
Expert Analysis and Future Outlook
While the current downward trend in interest rates is welcomed, financial experts caution against assuming that this trajectory will continue indefinitely into 2027. The primary challenge remains the potential mismatch between credit demand and deposit mobilization.
Dr. Le Xuan Nghia, a member of the National Financial and Monetary Policy Advisory Council, emphasizes that while current directives are effective in the short term, they are contingent upon market conditions. "The interest rate environment is inextricably linked to macroeconomic stability, specifically the management of inflation and exchange rates," Dr. Nghia noted. "Lowering rates is a sustainable policy only if the economy remains buffered against external shocks and if domestic banking liquidity remains robust."
Looking toward the remainder of 2026 and into 2027, the outlook is one of cautious optimism. Securities firms, such as Rong Viet Securities (VDSC), suggest that while deposit rates may continue to decline or remain stable for the rest of 2026, a sharp or sustained drop in 2027 is unlikely. The structural demand for long-term capital to fund infrastructure and industrial expansion remains a significant factor that will constrain the extent to which rates can fall.
Broader Economic Implications
The success of these monetary interventions highlights the critical role of the banking sector in facilitating national industrial policy. By directly reducing the "cost of money" for manufacturers, the SBV is effectively subsidizing the real economy without the need for direct fiscal spending.
However, the implications go beyond just interest rates. The focus on supporting existing loans—ensuring that businesses with current debt burdens see the benefit of lower rates immediately—is a vital component of this strategy. It allows companies to manage their cash flow more effectively, avoiding the risk of default during the volatile transition from one fiscal year to the next.
As Vietnam moves into the final months of 2026, the synergy between the central bank’s liquidity management and the proactive efforts of commercial lenders will remain the linchpin of industrial stability. The ability to maintain these rates at a "reasonable level" will depend on the continued coordination between monetary policy and the broader macroeconomic goals of controlling inflation and maintaining a stable exchange rate.
For the thousands of businesses awaiting the outcome of these policies, the message is clear: the current environment is designed to reward productivity and stability. As long as inflationary pressures remain contained and global market conditions remain supportive, the current monetary framework provides a solid foundation for continued economic expansion in the coming year. The focus now shifts to whether this liquidity can be efficiently channeled into high-growth sectors, ensuring that the benefits of lower capital costs are translated into sustained industrial output and job creation.
Related posts: