Oil and gas enterprises in Vietnam post record nine-month profits amid market volatility while facing persistent working capital pressures

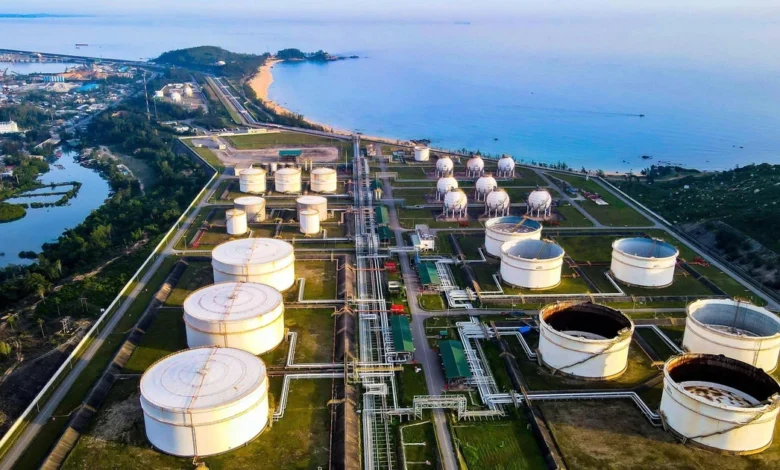
The Vietnamese oil and gas sector has navigated a complex financial landscape throughout the first nine months of 2026, characterized by dramatic swings in global crude prices and significant shifts in supply chain dynamics. Despite these fluctuations, major players across the value chain—from refining to retail distribution—have reported extraordinary year-on-year profit growth. However, this surge in profitability masks a more precarious underlying reality: many of these industry giants are grappling with significant cash flow constraints and a constant, heavy demand for working capital to maintain operations in a high-cost environment.
A Period of Unprecedented Growth
The financial reports for the third quarter of 2026 reveal a stark contrast to the previous year. The most prominent example of this success is the Binh Son Refining and Petrochemical Joint Stock Company (BSR), the operator of the Dung Quat Oil Refinery. During the third quarter, BSR recorded net revenue of approximately 59.6 trillion VND, a 69% increase compared to the same period in 2025.
While revenue growth was substantial, the company managed to control its cost of goods sold, which rose by roughly 46%. This efficiency, combined with the favorable pricing environment, allowed BSR to report a net profit of nearly 9.65 trillion VND for the quarter—a figure nearly ten times higher than the same period last year and a historic quarterly record for the firm.
For the first nine months of 2026, BSR’s cumulative net revenue reached over 164.2 trillion VND, representing a 58% increase. The net profit after tax surged to over 24.9 trillion VND, approximately 11.6 times higher than the nine-month results from the prior year. According to BSR, the primary driver for this windfall was the high price of Brent crude, which averaged roughly 97 USD per barrel in the third quarter, compared to approximately 69 USD per barrel during the same period in 2025. Additionally, the improved crack spread—the price difference between crude oil and finished petroleum products—provided a significant boost to margins.
The Downstream Landscape: Petrolimex and PVOIL
The positive trend was not limited to the refining segment. Downstream distributors, tasked with the critical role of bringing fuel to the end consumer, also experienced a banner year.
The Vietnam National Petroleum Group (Petrolimex), the largest player in the retail segment, reported third-quarter net revenue of nearly 138.5 trillion VND, a 66% increase year-on-year. Their net profit after tax hit 1.36 trillion VND, a 93% jump. Aggregated over the first nine months, Petrolimex saw revenue reach 373.2 trillion VND, with a net profit of 3.75 trillion VND, reflecting a 60% growth rate compared to the same period in 2025. With these figures, Petrolimex firmly maintains its position as the largest revenue generator in the sector.
Meanwhile, the PetroVietnam Oil Corporation (PVOIL) witnessed a more dramatic turnaround. Following a difficult second quarter where the company posted a loss of over 95 billion VND, the third quarter saw a remarkable reversal. PVOIL reported quarterly net revenue of over 90.4 trillion VND, a 176% increase. Their net profit after tax reached nearly 774 billion VND—a 5.6-fold increase that set a new quarterly record. For the nine-month period, PVOIL achieved a net profit of 1.27 trillion VND, already surpassing its full-year target by 94%.
Even smaller players, such as the Petroleum Material and Equipment Joint Stock Company (COMECO), participated in this growth, reporting a nine-month net profit of 32 billion VND, a 163% increase from the previous year.
The Paradox of Cash Flow and Working Capital
Despite these robust earnings, the internal financial health of these companies presents a more nuanced picture. The primary challenge remains the management of cash flow. Because petroleum is a capital-intensive commodity, companies must maintain massive inventories and manage extensive accounts receivable, both of which are highly sensitive to global price fluctuations.
At Petrolimex, while the company reported a net cash flow from operating activities of nearly 2.5 trillion VND for the first nine months—an improvement over the 1.16 trillion VND deficit seen in the same period last year—the underlying data reveals the strain. Specifically, fluctuations in inventory levels reduced cash flow by over 15.6 trillion VND, while changes in payables helped boost cash flow by approximately 15.3 trillion VND. This balancing act illustrates the constant, urgent need for working capital as the business scales.
PVOIL faces a similar reality. By the end of September, the company’s short-term accounts receivable had climbed to over 30 trillion VND, representing approximately 46% of its total assets. This heavy reliance on credit sales and the delay in payment cycles can tie up vast amounts of liquidity, leaving companies vulnerable if market conditions were to shift suddenly. Furthermore, PVOIL’s gross profit margin during the third quarter actually dipped from 3.1% to 2.7%, suggesting that while revenue is high, the cost of maintaining market share and managing distribution is tightening margins.
Industry Context and Macroeconomic Implications
The volatility in the oil and gas sector during 2026 is largely a reflection of the broader geopolitical landscape. Supply chain disruptions in major oil-producing regions have kept global benchmarks like Brent crude elevated. For a nation like Vietnam, which relies on a mix of domestic refining and imports, these price movements have a direct impact on national inflation and the operational stability of energy firms.
Historically, the government has monitored these companies closely to ensure the security of national fuel supplies. The fact that distributors and retailers are reporting high profits during periods of extreme price volatility often triggers intense public and regulatory scrutiny regarding fuel pricing mechanisms. While the profits are technically a result of inventory valuation and market spreads, there is often pressure from the public to lower retail prices when wholesale costs stabilize.
Looking Ahead: Financial Resilience
The divergent financial health of these companies offers a lesson in risk management. Companies like BSR, which hold significant cash reserves (nearly 58.65 trillion VND in cash and bank deposits compared to debt of 13.5 trillion VND), are better positioned to weather sudden market shocks. In contrast, distributors operating on thin margins and high turnover—like COMECO or PVOIL—are more reliant on debt facilities and efficient cash cycle management.
As the industry moves into the final quarter of 2026, the primary challenge for leadership teams will be to convert these accounting profits into tangible liquidity. Should global crude prices enter a period of prolonged decline, the companies will face the double-edged sword of inventory write-downs and the potential for reduced margins, which could quickly erode the gains recorded in the first nine months.
Ultimately, the 2026 financial performance of Vietnam’s oil and gas giants underscores the sector’s vital role in the economy. While record-breaking profits suggest a period of success, the underlying data confirms that the business of energy remains inherently volatile, requiring sophisticated financial hedging, robust inventory management, and a constant focus on liquidity to ensure that the lights remain on and the fuel keeps flowing across the nation.
Related posts: