Danang Housing Investment Development Corporation Reports Q3 2026 Loss Amid Slumping Financial Revenues and Heavy Stock Portfolio Exposure

Danang Housing Investment Development Corporation, publicly traded under the Ho Chi Minh Stock Exchange ticker NDN, has officially released its consolidated financial statements for the third quarter of 2026, revealing a sharp downturn in business performance. The company reported a net loss after tax of approximately VND 10 billion for the quarter, reversing the profitable trajectory seen during the same period in the previous year when it recorded a net profit of VND 71 billion. This reversal underscores the immense volatility faced by real estate and investment firms operating in a fluctuating macroeconomic environment, where traditional core operations and financial market exposures heavily dictate quarterly outcomes.
The financial results for the three months ending September 30, 2026, highlight widespread pressure across multiple revenue streams. Net revenue from sales and services reached a modest VND 7 billion, representing a 19% decrease compared to the corresponding period in 2025. Cost of goods sold saw a more moderate decline of 14% to stand at approximately VND 4 billion, resulting in a gross profit of roughly VND 3 billion—down 24% year-over-year. Consequently, the company’s gross profit margin experienced a slight contraction, slipping from 47% in the third quarter of 2025 to 44% in the current reporting period.
Financial Activities and Operational Pressures
The most dramatic variance in NDN’s third-quarter financial statement stemmed from its financial activities, which historically serve as a significant profit driver for the enterprise. During the quarter, financial revenue plummeted by 85%, dropping sharply from VND 97 billion in the third quarter of 2025 to just VND 15 billion. Conversely, financial expenses surged by 92% to reach VND 26 billion, compounding the downward pressure on overall profitability.

Operating expenses remained relatively contained but failed to offset the severe contraction in financial income. Selling expenses were slashed by 47% to approximately VND 100 million, while general and administrative expenses decreased by 7% to roughly VND 2 billion. Nevertheless, the combination of declining core revenues, shrinking financial gains, and soaring financial costs pushed NDN into an operating loss of VND 11 billion for the quarter, a stark contrast to the operating profit of VND 85 billion recorded in the third quarter of the previous year.
Before tax, the company reported a loss of VND 11 billion, which translated to a net loss of VND 10 billion after accounting for tax considerations. For the first nine months of 2026, NDN recorded cumulative net revenue of VND 32 billion, reflecting a 60% increase compared to the same timeframe last year. However, due to the severe headwinds encountered in the subsequent quarters, cumulative pre-tax profit dropped by 88% to VND 19 billion, while net profit fell by 89% to VND 15 billion. Against the full-year 2026 targets of nearly VND 75 billion in total revenue and at least VND 37 billion in net profit, the company has completed roughly 40% of its annual profit objective with only one quarter remaining in the fiscal year.
Equity Portfolio Dominates Balance Sheet
A defining characteristic of NDN’s financial structure remains its heavy allocation toward short-term trading securities, which comprised nearly half of the firm’s total assets as of September 30, 2026. Total assets stood at nearly VND 1.378 trillion, marking an increase of VND 21 trillion compared to the end of the second quarter. Within this asset pool, cash and cash equivalents, including bank deposits, accounted for approximately VND 223 billion.
Most notably, NDN maintained a trading securities portfolio with a fair value exceeding VND 760 billion. Compared to the end of the second quarter, the total historical cost of the stock portfolio increased by roughly VND 8.5 billion to reach nearly VND 668 billion. However, the aggregate fair value of these holdings decreased by approximately VND 63 billion over the same period, reflecting broader market fluctuations that impacted asset valuations.

To safeguard against potential downside risks within its equity holdings, NDN increased its provision for the devaluation of trading securities. By the close of the third quarter, the total provision reached nearly VND 51 billion, expanding by approximately VND 24 billion compared to the second quarter figures.
Performance Breakdown of Key Equity Holdings
A detailed examination of NDN’s investment portfolio reveals mixed performances across several blue-chip stocks listed on the Vietnamese stock market. The company’s investment in Vinhomes JSC (ticker: VHM) stood out as the most lucrative position. With a historical cost of nearly VND 84 billion, the fair value of the VHM stake surged to nearly VND 185 billion by the end of September. This generated an estimated unrealized profit of approximately VND 101 billion, making it by far the largest positive variance among all individually disclosed stock holdings in the portfolio.
Conversely, the performance of other major holdings varied. For shares of China Steel/Hoa Phat Group (ticker: HPG), NDN recorded a historical cost of nearly VND 110 billion, up nearly VND 18 billion from the end of the second quarter. The fair value of the HPG stake reached nearly VND 123 billion, remaining relatively stable compared to June figures and yielding an unrealized profit of approximately VND 13 billion.
The investment in Vietnam Prosperity Joint Stock Commercial Bank (ticker: VPB) yielded a fair value of nearly VND 40 billion, translating to an unrealized gain of approximately VND 2 billion. Meanwhile, Military Commercial Joint Stock Bank (ticker: MBB) recorded a historical cost of nearly VND 71 billion—a decrease of nearly VND 7 billion from the previous quarter—with a fair value of approximately VND 76 billion, resulting in an unrealized profit of roughly VND 5 billion.

On the other hand, holdings in other sectors faced downward pressure. For instance, the investment in GELEX Group (ticker: GEX) carried a historical cost of nearly VND 52 billion, showing a minor increase from the second quarter. However, the fair value of GEX shares dropped significantly from nearly VND 59 billion down to approximately VND 46 billion, resulting in an unrealized loss of roughly VND 6 billion. Other miscellaneous equity investments carried a total historical cost of nearly VND 313 billion against a fair value of VND 291 billion, sitting about VND 22 billion below their initial acquisition costs.
Real Estate Holdings and Strategic Outlook
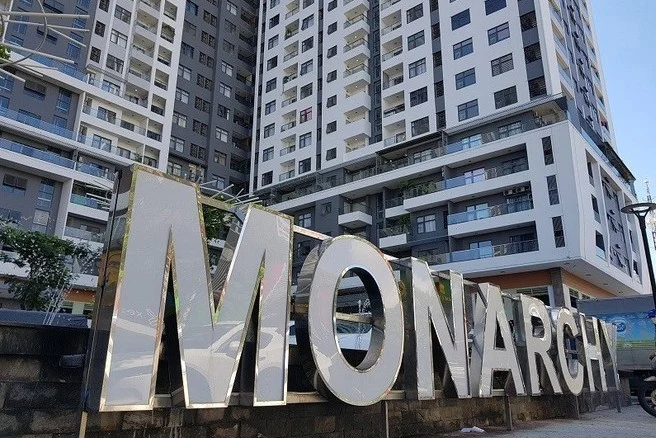
Beyond its substantial securities portfolio, NDN maintains a portfolio of investment properties. As of September 30, the remaining value of these real estate assets stood at approximately VND 239 billion, with the vast majority tied to the high-profile Monarchy residential project in Danang.
The heavy reliance on both financial market investments and real estate development places NDN in a unique strategic position. While equity investments offer substantial upside potential during bull markets—as demonstrated by the strong gains in the VHM holding—they simultaneously expose the corporation’s bottom line to heightened volatility when equity valuations correct. With the final quarter of 2026 underway, market observers will closely monitor whether management can accelerate core real estate sales or leverage its robust cash reserves and investment portfolio to bridge the gap toward its full-year financial objectives.