HoREA proposes allowing the sale of social housing at market prices after five years of ownership

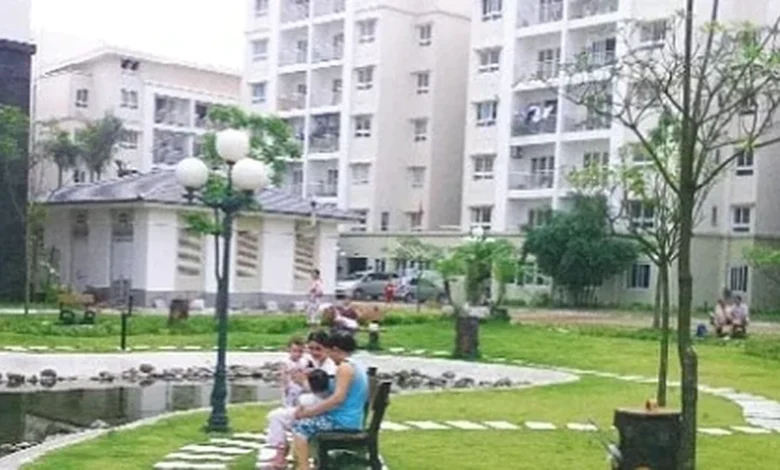
The Ho Chi Minh City Real Estate Association (HoREA) has officially submitted a formal petition, document number 147/2026/CV-HoREA, to the Prime Minister and relevant regulatory bodies, proposing a significant shift in the legal framework governing social housing (NƠXH) transactions. The association is advocating for an amendment to Article 68, Clause 1, Item e of the draft Law on Housing, which currently restricts the transfer of social housing units even after the mandatory five-year holding period has elapsed. This proposal aims to align social housing policies with market-based mechanisms, ensuring that buyers can recoup their actual investments while preventing the "black market" for real estate transactions that has emerged due to current restrictive regulations.
The Current Regulatory Landscape and its Limitations
Under the existing draft of the Law on Housing, social housing owners are subject to strict limitations during the first five years of occupancy. During this period, owners are permitted to sell their units only to the original project developers or to other individuals who meet the stringent eligibility criteria for social housing. Crucially, the selling price is capped at the original contract price, effectively prohibiting any capital gains or adjustments for inflation, maintenance costs, or interest expenses.
HoREA argues that this rigid pricing structure is disconnected from economic reality. When a homebuyer purchases a social housing unit, they incur a variety of "hidden" costs that go beyond the base price recorded in the purchase contract. These include interest payments on bank loans, early repayment penalties, the opportunity cost of the initial down payment, the mandatory 2% maintenance fund contribution, and various registration and administrative fees.
For example, on a loan of 1 billion VND with an initial interest rate of 5.9% per annum, a homebuyer would pay approximately 59 million VND in interest during the first year alone—amounting to nearly 4.9 million VND per month, excluding the principal repayment. If that buyer is forced to sell the property at the initial contract price, they face a guaranteed financial loss, rendering the investment unsustainable and discouraging participation in the social housing sector.
Implications: The "Double Price" Market
The association’s analysis suggests that the current restrictive policy is inadvertently fostering an underground market. Because the official, regulated price fails to reflect the actual financial burden placed on the seller, many transactions are being conducted as "double price" deals. In these scenarios, the official contract is signed at the state-capped price, while a secondary, private agreement is made to transfer the "difference" in cash outside of the legal contract.
This practice not only risks tax evasion and legal disputes but also creates a barrier to entry for legitimate, lower-income buyers who cannot afford to pay the "under-the-table" premium required by sellers. By keeping the market artificially constrained, the current regulation fails to protect the intended beneficiaries and instead complicates the secondary market for affordable housing.
Proposed Mechanism for Reform
To address these systemic issues, HoREA has proposed a two-tiered mechanism that separates the rules for the first five years from the period thereafter.
-
The First Five-Year Period: While maintaining the restriction that sales must be limited to eligible buyers or the original developer, HoREA suggests that the selling price should be adjusted to reflect actual costs. This would include the base contract price, accumulated bank interest, capital costs for the down payment, and a cost-of-living adjustment based on the Consumer Price Index (CPI). For down payments of up to 30% of the contract value, the association proposes that capital costs be calculated based on the 13-month term savings interest rates of the four major state-owned commercial banks.
-
Post-Five-Year Period: Once the five-year mandatory holding period has passed, HoREA proposes that the property should be allowed to trade freely at market prices. If the owner has received the Certificate of Land Use Rights and Ownership of Houses (the "red book"), the transaction should follow standard market rules. If the certificate has not yet been issued, the owner should be permitted to transfer the purchase contract or lease-purchase agreement to any individual interested in the property.
Furthermore, regarding the contentious issue of land use fees, HoREA strongly supports the adoption of "Option 2" within the draft Law on Housing. This option dictates that social housing owners should not be required to pay additional land use fees when transferring their properties after the five-year period, as these costs are typically accounted for in the initial development incentives.
Strengthening Eligibility and Preventing Speculation
Acknowledging concerns regarding potential speculation, HoREA has also proposed tightening the criteria for those wishing to benefit from social housing policies. The association suggests that buyers or lease-purchasers must have a permanent residency registration (ho khau) in the province or city where the project is located. If they lack permanent residency, they should be required to provide proof of temporary residency (tam tru) for at least one year at the local level. Furthermore, after purchasing the unit, the owner would be mandated to register for permanent residency at the address of the social housing unit, ensuring the property is used as a primary residence rather than for speculative investment.
Evidence of Market Cooling
The urgency of these reforms is underscored by recent observations from major developers. Firms such as Kim Oanh Group, Hung Thinh, Dat Xanh, Lan Hung, and Hung Loc have reported a concerning trend: potential buyers are withdrawing their applications for social housing as soon as the draft laws regarding these restrictions are publicized.
The psychology of the market is clear: prospective buyers are hesitant to commit to a long-term, high-value asset if they perceive that their rights to that asset—specifically their ability to liquidate the property during a personal financial crisis—are severely curtailed. When families face life events such as job relocation, health emergencies, or sudden shifts in financial circumstances, the inability to sell their property at a fair market value forces them into precarious situations.
Official Responses and Future Outlook
In discussions with the media, representatives from the Department of Housing and Real Estate Market Management under the Ministry of Construction have acknowledged that the ministry is actively researching the pricing regulations for post-five-year social housing sales. Officials have emphasized that they are weighing input from various stakeholders, including developers, legal experts, and social advocates.
The ministry’s primary challenge remains balancing two competing objectives: providing a stable, affordable living environment for low-income populations and preventing the social housing sector from becoming a vehicle for property speculation. While the goal of providing affordable shelter is paramount, the ministry appears to be moving toward an understanding that a more flexible secondary market is necessary to keep the social housing sector vibrant and attractive to both buyers and developers.
As the legislative process continues, the proposal from HoREA serves as a critical bridge between current restrictive policy and a more market-oriented approach. If adopted, these changes could significantly boost confidence in the social housing sector, encourage more households to step forward as buyers, and ultimately accelerate the government’s target of building one million social housing units by 2030.
Conclusion
The debate over the transferability of social housing is indicative of the broader challenge of managing a developing real estate market in Vietnam. While strict regulations were initially intended to prevent the "flipping" of units by wealthy investors, they have inadvertently created a bottleneck that traps low-income owners in properties they cannot easily exit. By refining the definition of "market price" to include legitimate financial costs and by introducing a more transparent framework for secondary transactions, the government has the opportunity to professionalize the social housing market. This shift would ensure that social housing serves its true purpose: providing a secure, liquid, and affordable housing foundation for the nation’s workforce, while protecting the financial integrity of the families who call these developments home.
Related posts: