PC1 Group Reports 27 Percent Jump in Nine-Month Profit Despite Revenue Compression Amid Strategic Shifts

CTCP Tập đoàn PC1 (HOSE: PC1) has released its consolidated financial statement for the third quarter of 2026, outlining a complex financial picture characterized by lower top-line revenues offset by improved profit margins, stronger earnings from subsidiary operations, and ongoing capital restructuring. While consolidated net revenue contracted during the quarter and across the first nine months of the year, disciplined cost management and positive contributions from key real estate projects allowed the company to deliver solid bottom-line growth.
Third-Quarter Performance: Revenue Down, Margins Up
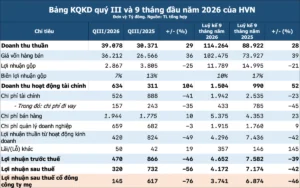
For the third quarter of 2026, PC1 reported consolidated net revenue of VND 2,619 billion, representing a 20% decline compared to the same period in the previous year. Despite the contraction in top-line figures, the company’s cost of goods sold dropped at a faster rate of 27%, decreasing to VND 1,896 billion. This reduction in production and operating costs helped drive the enterprise’s gross profit up by 6% to VND 724 billion. Consequently, PC1’s gross profit margin showed marked improvement, expanding from 21% in the third quarter of 2025 to 28% in the current reporting period.
Financial activities also provided a positive boost during the quarter. Financial revenue surged by 78% to reach VND 95 billion. In contrast, financial expenses experienced a modest increase of 4%, totaling VND 210 billion, with interest expenses alone accounting for VND 201 billion—a 15% rise compared to the corresponding period last year.

Operating expenses showed mixed movements. Selling expenses decreased by 25% to VND 22 billion, while general and administrative expenses rose by 5% to VND 112 billion. As a result of these financial dynamics, PC1 recorded a consolidated net profit after tax of VND 416 billion, marking a 6% increase year-on-year. However, the net profit attributable to shareholders of the parent company declined by 14% to VND 258 billion, reflecting minority interest distributions and shifts in subsidiary profit allocations.
Nine-Month Results and Progress Toward Annual Targets
Looking at the broader picture for the first nine months of 2026, PC1’s cumulative net revenue reached VND 6,825 billion, down 15% compared to the same timeframe in 2025. Despite the lower revenue, cumulative net profit after tax advanced significantly by 27% to reach VND 894 billion. Of this total, the profit attributable to shareholders of the parent company stood at VND 569 billion, representing a 14% increase.
Management attributed the positive profit performance primarily to contributions from the Thap Vang staggered real estate project, which generated steady revenue and earnings during the period, contrasting with the previous year when the project was still in its early development phases. Furthermore, various subsidiaries and affiliated companies distributed higher dividend yields and delivered stronger profit contributions compared to a year prior.
For the full year 2026, PC1 has set a consolidated revenue target of over VND 15,618 billion and a net profit after tax target of VND 1,056 billion. Having completed the first nine months of the fiscal year, the enterprise has achieved approximately 44% of its annual revenue plan and an impressive 85% of its full-year profit objective, placing the company in a strong position to meet its annual bottom-line commitments.

Balance Sheet Structure: Total Assets and Financial Position
As of September 30, 2026, PC1’s total assets stood at nearly VND 23,962 billion, marking a reduction of over VND 884 billion compared to the end of the second quarter of 2026. Fixed assets accounted for approximately VND 8,226 billion, representing roughly 34% of total assets, while cash and cash equivalents, along with bank deposits, reached nearly VND 4,736 billion.
In terms of financial investments, PC1 held 85,074 shares of Vietnam Joint Stock Commercial Bank for Investment and Development (BIDV – HOSE: BID) with an initial cost of nearly VND 822 million. By the end of September, the fair value of this investment had risen to nearly VND 3 billion, translating to an unrealized gain of more than VND 2.2 billion over its original cost.
Conversely, the company maintained an investment of VND 4 million in 400,000 shares of CTCP Bê tông Lệ Tấm Vinaincon, for which a full impairment provision has been recorded. According to the financial statement notes, management has not yet determined the fair value of this particular investment because current Vietnamese accounting standards and regulations lack detailed guidelines regarding fair value assessments for such unlisted financial instruments.
The company’s owners’ equity reached nearly VND 9,540 billion as of September 30, which included nearly VND 2,203 billion in undistributed post-tax profits.

Debt Profile and Key Creditors
Total outstanding debt for PC1 reached approximately VND 10,880 billion at the end of the third quarter. This total debt structure comprised VND 2,378 billion in short-term borrowings, VND 8,203 billion in long-term borrowings, and nearly VND 299 billion in bonds. Short-term debt obligations included VND 1,164 billion in long-term loans and nearly VND 299 billion in bonds that are due for repayment within the next 12 months.
Short-term borrowings carried maturities of under 12 months and were utilized primarily to supplement working capital needs. State-owned commercial banks played a dominant role in providing liquidity, with VietinBank emerging as the largest creditor with VND 1,836 billion, followed by BIDV with VND 333 billion. The remaining short-term debt of approximately VND 209 billion was distributed among international and domestic institutions, including HSBC, Vietcombank, Bank of China, Shinhan Bank, and other financial partners.
In the long-term debt segment, PC1 held approximately VND 2,691 billion in US Dollar-denominated loans, primarily sourced from international development finance institutions such as the Asian Development Bank (ADB), Export Finance Australia, and the Japan International Cooperation Agency (JICA). These foreign currency loans were secured by assets originating from three major wind power projects: Lien Lap, Phong Huy, and Phong Nguyen.
Meanwhile, long-term VND-denominated debt stood at approximately VND 5,512 billion, largely concentrated within BIDV, Techcombank, VietinBank, and Vietcombank. Collateral for these domestic loans included hydro-power projects, the nickel-copper mining and processing plant in Quy Hop, the Nomura – Hai Phong Industrial Park phase 2 development, and guarantees provided by related corporate entities.

Additionally, PC1 maintained a corporate bond lot with a par value of VND 300 billion and a book value of nearly VND 299 billion, maturing in 2027. The bonds are secured by PC1 shares held by related individuals. Financial disclosures indicate that the proceeds from this bond issuance were deployed toward industrial real estate investments through the acquisition of shares in CTCP Western Pacific, alongside supplementing general working capital requirements.