MWG Reports Robust 10-Month Revenue Surge Driven by Strong Domestic Performance and EraBlue Expansion in Indonesia

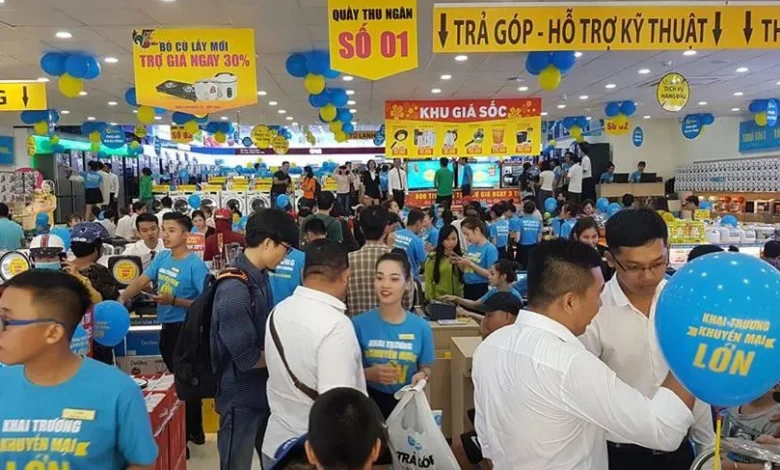
The retail landscape in Southeast Asia continues to undergo structural shifts as major consumer electronics and appliance chains adapt to changing macroeconomic realities. Amid shifting consumer behaviors and cautious discretionary spending in broader markets, prominent Vietnamese multi-sector retail enterprise Mobile World Investment Corporation (commonly known as Thế Giới Di Động or MWG) has released its financial performance report for the first ten months of the year. Demonstrating resilience and strategic operational agility, the corporation posted substantial top-line growth, fueled by strong same-store sales performances, expanding digital channels, and the aggressive regional scaling of its joint-venture retail model in Indonesia.
According to the official financial disclosure, MWG recorded a consolidated net revenue of VND 112,430 billion during the January-October period. This figure represents an impressive 28% increase compared to the corresponding period in the previous year, achieving approximately 92% of the enterprise’s total revenue target set for the entirety of the fiscal year. On average, the corporation generated nearly VND 370 billion in daily revenue throughout this ten-month span, underlining sustained high-volume consumer demand across its extensive retail ecosystem.
The momentum culminated in October alone, during which monthly revenue surpassed VND 12,900 billion. This represented a 4% sequential increase from September and marked the highest monthly sales figure recorded by the corporation since the beginning of the year. Industry analysts note that this performance reinforces the underlying health of the company’s operating segments and validates its shift away from aggressive physical footprint expansion toward optimizing existing retail spaces.
Strong Performance Across Core Retail Pillars and Same-Store Sales Growth
A detailed breakdown of the financial report reveals that revenue growth was achieved across all five primary business pillars, with the vast majority of the acceleration stemming from organic store improvements rather than the opening of new brick-and-mortar locations. The Same-Store Sales Growth (SSSG) metric climbed by an impressive 29%, indicating that existing retail points are generating significantly higher transactional value per square meter.
Examining performance by retail chains within the corporate umbrella, Điện Máy Xanh (electronics) maintained its position as the primary revenue engine, contributing 65% of the total consolidated top-line. Meanwhile, Thế Giới Di Động (ICT and mobile retail) accounted for 31%, and the Apple-focused premium reseller chain TopZone made up the remaining 4%.
On a comparative basis, the revenue of all three domestic chains demonstrated robust double-digit growth during the ten-month period:

- Điện Máy Xanh increased by 28% year-on-year.
- Thế Giới Di Động grew by 28% year-on-year.
- TopZone led the growth charts with a 34% increase compared to the same period last year.
TopZone’s outperformance was heavily catalyzed by surging consumer demand for Apple devices, which expanded by 50%. This segment received a significant seasonal boost in October driven by the nationwide official delivery and rollout of the highly anticipated iPhone 18 series and iPhone Duo models, drawing large crowds of technology enthusiasts to physical showrooms.
Strategic Catalysts: Zero-Interest Installment Plans and Portfolio Diversification
To stimulate purchasing power in a market where consumers remain conscious of household expenditures, MWG successfully deployed a series of targeted commercial strategies. Key growth drivers included competitive promotional policies such as 0% interest installment plans, enhanced after-sales customer care services, and a broader diversification of product portfolios across all major product categories.
Among these initiatives, the zero-interest installment payment model emerged as a crucial growth multiplier. Revenue generated through installment schemes surged by 52% year-on-year. Consequently, installment transactions expanded their contribution to 39% of total sales, up from 33% during the same period in the previous year. Company data indicates that approximately 96% of MWG’s entire product catalog is now eligible for flexible installment financing, substantially lowering the financial barrier to entry for high-value purchases such as premium smartphones, large-screen televisions, and advanced home appliances.
Analyzing performance by product category, the Information and Communication Technology (ICT) sector commanded 57% of total revenue, followed by consumer electronics and home appliances at 38%, and services at 5%. Specifically, mobile phones across both Apple and Android operating systems captured a combined market share of 22%, while the home appliance and kitchenware segment contributed 10%.
Digital Transformation, Omnichannel Strength, and Financial Services
While physical storefronts remain the cornerstone of retail distribution—accounting for 85% of total revenue—MWG’s digital channels demonstrated exceptional vitality. Online revenue surged by 40% year-on-year, reaching VND 16,322 billion and accounting for 15% of the corporate total.
This digital expansion is closely tied to the robust adoption of the corporation’s proprietary Super App ecosystem, which amassed 19.8 million registered members by the end of October, adding roughly 1.9 million new users since the start of the year. The platform serves as a vital engagement tool, facilitating seamless cross-channel marketing, personalized promotions, and integrated customer loyalty tracking.
In the service sector, Điện Máy Xanh generated VND 3,006 billion, reflecting a 38% year-on-year increase. Within this division, revenue generated from external customers outside the traditional retail ecosystem reached VND 384 billion, up 44% and representing 13% of the total service segment revenue.

Furthermore, MWG’s financial technology and utility payment services continued to operate at scale, processing VND 92,000 billion in total transaction value. The service facilitated approximately 60 million individual transactions across more than 3,000 participating retail locations, reinforcing the company’s dual identity as both a consumer goods retailer and a foundational neighborhood financial access point.
Network Optimization and the Rapid Ascent of EraBlue in Indonesia
MWG’s physical footprint strategy underwent targeted rebalancing during the first ten months of the year. By the close of October, the corporation operated a total network of 3,373 stores across all brands, representing a net addition of 185 sales points compared to the same period last year and 172 points since January.
The most notable expansion occurred internationally through EraBlue, MWG’s joint-venture electronics retail chain in Indonesia. EraBlue spearheaded the network growth by adding 211 stores year-on-year and 188 stores since the beginning of the year, bringing its total active footprint in the archipelago to 369 stores.
Operating in a high-potential foreign market, EraBlue reported revenue of VND 5,289 billion, surging 85% year-on-year when calculated in Indonesian Rupiah (IDR). Cumulative SSSG for the Indonesian chain rose by 12%. Encouraged by this strong international reception, MWG management has reaffirmed ambitious long-term targets, aiming to scale the EraBlue store network to 500 locations by 2027 and reaching the milestone of 1,000 stores by 2030.
Conversely, domestic network adjustments reflected a consolidation and efficiency-focused strategy. The number of traditional Điện Máy Xanh stores decreased by 20 points year-on-year to 1,998 locations. Similarly, Thế Giới Di Động outlets contracted by 7 points down to 920 locations, while the premium TopZone chain saw a net addition of one store, standing at 86 locations. Management noted that closing underperforming or overlapping domestic locations while reallocating capital toward high-efficiency stores and international expansion has successfully optimized operating margins without sacrificing top-line growth.
Outlook and Fourth-Quarter Projections
As MWG enters the final quarter of the fiscal year, corporate leadership remains optimistic. The upcoming peak shopping season—traditionally marked by heightened consumer demand around year-end festivities, promotional campaigns such as Black Friday, and the ongoing sales momentum generated by the iPhone 18 series—is expected to provide a robust operational tailwind.
By capitalizing on these seasonal catalysts and maintaining disciplined supply chain management, MWG aims to achieve its overarching annual guidance of a 30% year-on-year revenue increase. The corporation’s performance over the first ten months demonstrates that strategic flexibility, aggressive regional diversification into Indonesia, and consumer-centric financing models can successfully drive sustainable growth even amid a complex and evolving macroeconomic environment.