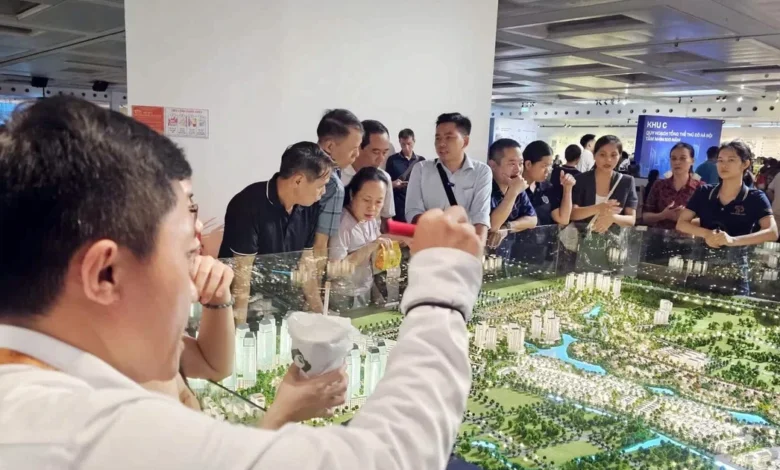
The Vietnamese real estate brokerage sector is currently navigating a period of profound financial instability, characterized by shrinking revenues, escalating operational overheads, and a systemic delay in commission settlements. According to the latest market health report for the third quarter of 2026 released by the Vietnam Association of Realtors (VARS), the industry is facing a precarious "cash flow squeeze" that has left many firms struggling to maintain solvency. While some entities have reported a marginal increase in top-line revenue compared to the same period in previous years, these figures are largely deceptive; bottom-line profitability has eroded due to surging administrative costs, mounting accounts receivable, and the substantial reserves required for bad debt provisions.
The Anatomy of the Financial Crisis
The current crisis represents a continuation of the turbulence that began in late 2024 and intensified throughout 2025. Data provided by VARS members indicates that the operational landscape has shifted dramatically. Between 2025 and 2026, approximately 65% of brokerage firms reported that the time required to collect commissions from developers has extended significantly, now ranging from six to twelve months. This liquidity gap is compounded by the fact that roughly 25% of all commissions remain "trapped" for over a year, or in many instances, have become the subject of protracted legal disputes between brokers and developers.
This delay in payment is not merely a bookkeeping issue; it is an existential threat. Brokerage firms, which typically operate on thin margins, are finding it increasingly difficult to sustain their core operations—including payroll, marketing, and office maintenance—when their primary source of income is indefinitely deferred.
Chronology of the Market Contraction
To understand the severity of the current situation, one must look at the timeline of the sector’s decline. In 2022 and 2023, the industry faced a shock due to tightened credit regulations and a series of high-profile defaults by major property developers. Many brokers pivoted by focusing on secondary market transactions and social housing to stay afloat.
By early 2025, there was a tentative hope for recovery as regulatory frameworks were updated to protect consumer rights and streamline project approvals. However, the anticipated rebound failed to materialize in the volume expected. By the second quarter of 2026, the volume of successful transactions had plummeted. As of the third quarter of 2026, market data shows a nearly 90% decline in transaction volume for many mid-sized brokerage agencies compared to the peaks of 2022. The market has effectively entered a period of stagnation, where only the largest, most transparent developers—those with impeccable track records and secure financing—are capable of sustaining consistent sales cycles.
The Disconnect Between Interest and Action
Despite the slump in actual sales, public interest in real estate has not entirely evaporated. Market research and online behavior tracking indicate that consumer interest in property remains remarkably stable. Potential buyers continue to conduct online searches, contact agents for consultations, and request site visits at a high frequency.
However, this interest has failed to translate into a corresponding surge in conversion rates. Industry analysts point to a "psychology of hesitation." Potential investors are adopting a wait-and-see approach, fueled by concerns over future economic stability, lingering questions about project legality, and the expectation of further price corrections. This cautious sentiment, while rational for the individual, creates a paralyzing effect on the broader market. When customers refuse to pull the trigger, the entire supply chain—from developers to marketing firms to individual brokers—suffers.
The Shift in Brokerage Strategy
In response to these mounting challenges, the role of the real estate broker is undergoing a fundamental transformation. According to Hoang Huu Minh Duong, Head of Research and Development at BHS Property, the industry is no longer a volume-based game. "The pressure on operating costs is increasing as the time taken to nurture a single client expands," Duong noted. "When the conversion rate drops, you cannot afford to waste resources on unqualified leads."
This necessity has forced firms to adopt a "quality over quantity" strategy. Brokers are now expected to prioritize projects with ironclad legal documentation and transparent developer credentials. The days of aggressive, high-pressure sales tactics are being replaced by a consultative approach. The Dat Xanh Services (DXS-FERI) research institute has suggested that brokers must evolve into comprehensive financial advisors. They must be capable of accompanying clients through the entire investment process, providing deep-dive analysis on legal, financial, and long-term valuation risks, rather than simply acting as a bridge between buyer and seller.
Institutional Challenges and Capital Access
A critical bottleneck remains the difficulty of accessing capital. For many small-to-medium-sized brokerages, the inability to prove stable financial health makes it nearly impossible to secure bank loans. This is exacerbated by the current lending environment. Banks, having tightened their risk management protocols following the real estate sector’s recent volatility, have become highly selective.
Pham Duc Toan, General Director of EZ Vietnam, highlights that the credit room for real estate remains extremely limited. "Large banks are now focusing almost exclusively on massive, blue-chip conglomerates," Toan stated. "Smaller firms, which form the backbone of the retail brokerage market, are left to survive on their own cash reserves. When those dry up, projects are forced to halt because the cost of capital is too high to justify continued construction without a steady flow of sales."
The Socio-Economic Implications
The ongoing distress in the brokerage sector has broader implications for the economy. Real estate contributes a significant portion of Vietnam’s GDP, and the brokerage industry is a vital component of this engine. A weakened brokerage sector means fewer successful transactions, which in turn leads to lower tax revenues for local governments and reduced employment opportunities for thousands of professionals in related fields, including construction, interior design, and legal services.
Furthermore, the "survival of the fittest" environment currently unfolding is likely to lead to significant market consolidation. Smaller agencies that lack the financial backing or the ability to pivot to a high-end, consultative model are expected to exit the market. This will likely result in a more concentrated, albeit potentially more professional, industry in the long run.
Future Outlook and Recommendations
As the industry looks toward the final months of 2026 and into 2027, the path to recovery remains complex. Industry leaders suggest that a return to stability will require more than just time; it requires a concerted effort to restore consumer confidence. This includes:
- Legal Transparency: Accelerated efforts by authorities to clear the legal backlog for major projects will be essential in reducing the risk profile for investors.
- Financial Support for Brokerages: Targeted credit facilities for smaller, well-managed brokerage firms could help prevent a total collapse of the distribution network.
- Enhanced Professionalism: Continued training for brokers to transition into roles as trusted financial consultants will be necessary to meet the needs of a more discerning and cautious buyer base.
The current situation is a painful, yet necessary, correction for the Vietnamese real estate market. The transition from an era of unchecked, speculative growth to a more sustainable, value-driven market is inherently disruptive. For the brokerage firms that survive this period, the future will likely involve a more stable, albeit less volatile, revenue model defined by long-term client relationships rather than quick, short-term gains.
In conclusion, while the financial strain on real estate brokers is severe, it is also a signal of a market in the midst of a necessary structural shift. By abandoning the unsustainable practices of the past and embracing a more analytical, service-oriented approach, the industry may eventually emerge more resilient, providing a more stable foundation for the broader national economy.
Related posts: