The Vietnamese real estate market is currently navigating a period of profound recalibration as developers’ aggressive sales stimulus packages—ranging from deep discounts of 20-30% to extended interest-rate subsidies—increasingly fail to move the needle on transaction volumes. Despite the influx of creative financial incentives, the market remains characterized by a disconnect between developer pricing strategies and the purchasing power of the average consumer.
The Erosion of Sales Stimulus Effectiveness
For much of the past two years, developers relied on a playbook of financial engineering to sustain momentum. In late 2023, when administrative hurdles were cleared for major projects in Ho Chi Minh City and neighboring provinces like Binh Duong, initial sales were strong. At that time, market sentiment was buoyed by optimism, and developers found they did not need to resort to heavy discounting to attract buyers.
However, the narrative shifted significantly by mid-2024. As of June, many developers were forced to implement drastic measures to maintain cash flow. These included zero-interest periods for 12 months, fixed interest rates of 8% for three subsequent years, and two-year management fee waivers. In some cases, developers even held prices stagnant rather than raising them by the projected 5% to keep units affordable. Despite these efforts, sales in several high-profile projects have reached only 35% of their original targets.
The situation is mirrored in Tay Ninh, where townhome projects offering 20% discounts, two-year interest subsidies, and inclusive interior furnishing packages have seen such lackluster traffic that subsequent sales launches have been postponed indefinitely. Even in Ho Chi Minh City, where a low-rise housing project offered a 30% discount for early settlement along with five-year interest rate support, market liquidity has shown only marginal improvement.
Market Data and The Widening Affordability Gap
Recent data from industry analysts underscores the severity of the slowdown. According to the One Mount Group, transaction volumes for residential property in Ho Chi Minh City fell by 83% quarter-on-quarter and 72% year-on-year during the third quarter. The absorption rate for new supply has been alarmingly low, with Savills reporting that only 25% of new apartment supply has been absorbed, while low-rise housing projects are seeing absorption rates as low as 14%.
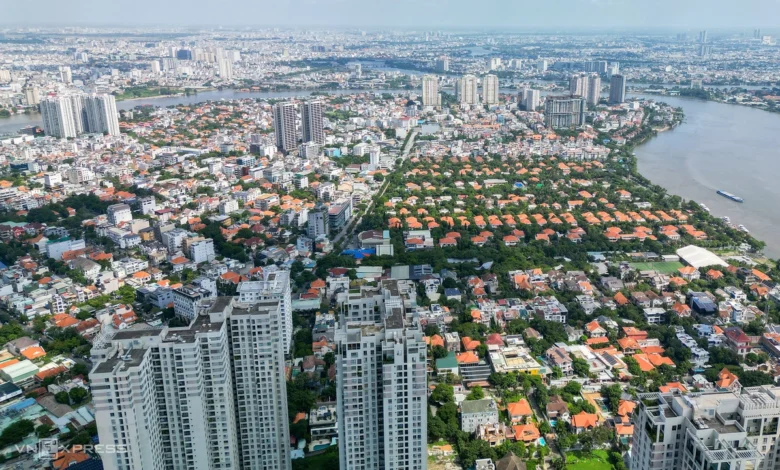
The fundamental barrier remains the pricing structure. The average price per square meter in central Ho Chi Minh City now hovers around 104 million VND, while Binh Duong and Ba Ria-Vung Tau have seen prices rise to 60 million and 67 million VND per square meter, respectively—representing year-on-year increases of 10%, 25%, and 27%. These figures demonstrate that while the "sticker price" continues to climb, the consumer’s ability to pay has not kept pace.
The Double Bind Facing Developers
Industry leaders are now acknowledging that indirect price reductions—such as interest subsidies and deferred payment schedules—are only temporary fixes that fail to address the core issue of overvaluation.

"Developers are caught in a double bind," says Le Quoc Kien, a prominent real estate consultant. "On one hand, development costs for land use, construction, and capital financing are rising. On the other hand, buyer confidence is eroding due to concerns over long-term debt obligations."
Kien argues that many of the current promotional programs are skewed toward short-term liquidity rather than long-term buyer value. A direct discount reduces the principal amount owed, whereas an interest-rate subsidy only provides a temporary buffer. Furthermore, "gimmicks" like furniture packages or vouchers hold little real-world value compared to the heavy burden of a multi-year loan.
Shifting Buyer Priorities
Consumer research, including surveys conducted by DXS-FERI, reveals a shift in what buyers prioritize. Legal transparency and developer credibility are now the top-tier criteria for 72-74% of potential buyers, followed by location and transport connectivity at 67%. Financial solutions are important, but they are increasingly being evaluated through the lens of long-term sustainability.
Cao Thi Thanh Huong, Deputy Director of Research and Consulting at Savills Ho Chi Minh City, notes that developers are hesitant to lower the base price of their products. "Developers prioritize adjusting sales policies over deep price cuts because they have to cover the high costs of project development," Huong explains. "Consequently, direct price reductions are limited, and the burden is shifted to the buyer to manage interest rate volatility."
Looking Ahead: A Market in Search of Equilibrium
As the market enters the final quarter of the year, experts predict that liquidity will likely remain suppressed. The industry is reaching a consensus that "stimulus fatigue" has set in. When buyers spend significant time analyzing the market, their decision-making process shifts away from the immediate gratification of a discount or a giveaway.
Instead, the market is moving toward a stage where success is defined by three pillars:
- Legal Certainty: The completion of legal documentation is non-negotiable for the modern investor.
- Product Suitability: Products that meet actual residential needs—rather than speculative investment needs—are the only ones seeing consistent, albeit slow, movement.
- Transparent Financial Structures: Buyers are now favoring straightforward pricing over complex financial instruments that hide the true cost of ownership.
The reliance on promotional "smoke and mirrors" is becoming a liability. For developers to regain momentum, they must confront the reality that current price points are unsustainable. Until there is a meaningful correction in base prices that aligns with the genuine purchasing power of the domestic market, even the most generous subsidies will likely continue to fall short of consumer expectations.
Conclusion
The current state of the Vietnamese real estate sector serves as a cautionary tale for a market that has long relied on high-growth expectations. The transition from a seller’s market to a buyer’s market is now complete, and the survivors will be those who pivot away from short-term promotional tactics and toward long-term affordability and trust-building. As interest rates remain a variable of concern and the cost of capital remains high, the coming months will likely force a necessary, if painful, price correction that could finally bring the market back to a state of long-term equilibrium.
Related posts: