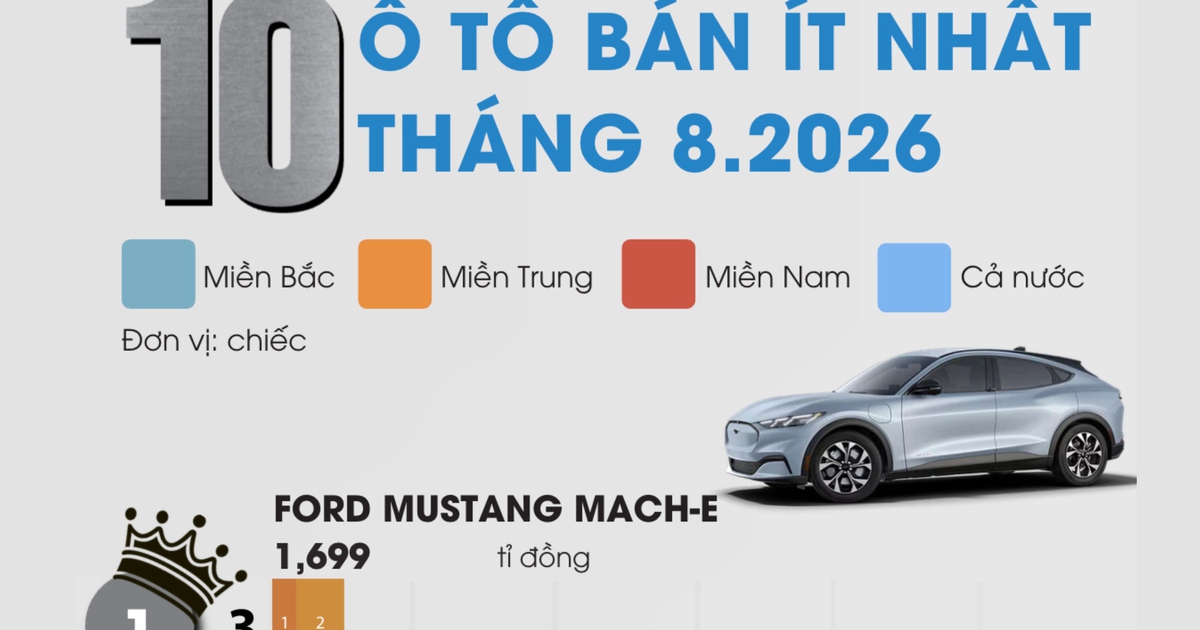
The automotive market in Vietnam experienced a notable shift in consumer preference and inventory dynamics throughout August 2026, culminating in a revealing list of the ten least-purchased vehicle models for the month. Data aggregated from industry reports indicates that while the broader market has shown signs of stabilization, several premium and specialized vehicle segments continue to face significant headwinds in retail performance. Notably, Toyota, typically a dominant force in the high-volume segment, found itself represented by four distinct models on this list of low-performers, highlighting the challenges of maintaining market saturation across diverse product lines, particularly within the luxury-leaning categories.
Market Context and Historical Trends
The Vietnamese automotive industry has been navigating a period of rapid evolution, characterized by the rise of electric vehicle (EV) infrastructure, fluctuating interest rates, and shifting import tax regulations. For the month of August 2026, the retail landscape reflected a distinct bifurcation: mass-market utility vehicles continue to command the highest sales volume, while premium and niche models are increasingly relegated to the periphery of consumer interest.
This trend is not entirely unexpected. Historically, the month of August—which often overlaps with the seventh lunar month, traditionally referred to in Vietnamese culture as a period where major purchases are avoided due to superstitions—consistently presents a seasonal lull in retail activity. However, the presence of four Toyota models on the "least sold" list signals that even established brands are not immune to the dual pressures of seasonal consumer hesitation and internal competition between their own high-volume offerings and their luxury-tier counterparts.

Analyzing the August 2026 Performance
The presence of multiple Toyota models in the bottom ten requires a nuanced analysis. Among the vehicles identified are primarily models categorized as premium sedans or specialized high-end SUVs. In many cases, these vehicles are priced at a premium that places them in direct competition with German luxury marques, which currently dominate the aspirational vehicle segment in Vietnam.
Industry analysts suggest that the cooling demand for these specific Toyota models is a result of "brand fatigue" in the premium segment. Consumers who are willing to spend significant capital on luxury vehicles are increasingly gravitating toward brands that offer more aggressive digital integration, distinct aesthetic departures from mass-market designs, and specialized service packages. Toyota, while maintaining an unassailable reputation for reliability, has faced difficulty in convincing the premium buyer that its high-end offerings provide the same "prestige value" as European competitors.
Chronology of Market Fluctuations
- Early Q1 2026: Market analysts predicted a slowdown in premium vehicle sales due to rising import costs and a shift in luxury tax brackets.
- May 2026: Mid-year data showed a marginal decline in interest for large-displacement, gasoline-powered SUVs, setting the stage for the August slump.
- August 2026: The traditional lunar-month hesitation coincided with a surplus of inventory for several premium models, leading to the low sales figures recorded at the end of the month.
- Post-August 2026: Manufacturers have begun recalibrating their marketing strategies, with some brands offering significant incentives, financing support, and extended warranty periods to clear existing stock before the end-of-year sales cycle.
Supporting Data and Segment Breakdown
The list of the ten least-sold vehicles in August 2026 is predominantly composed of vehicles that are either low-volume imports or models nearing the end of their product lifecycle. While total unit sales for the bottom ten remained in the single digits or very low double digits, the breakdown reveals a consistent theme:
- Luxury Sedans: These models continue to see the highest level of volatility. With the rise of electrification, traditional internal combustion engine (ICE) sedans are seeing their market share eroded by hybrid and full-electric alternatives.
- Specialized SUVs: Large-format SUVs with high fuel consumption are becoming increasingly unattractive to the average urban consumer in Vietnam, who is facing higher fuel costs and tightening emission regulations.
- Imported Niche Models: Vehicles that are brought into the country as Completely Built-Up (CBU) units often suffer from longer lead times and higher price points, making them susceptible to sudden drops in demand when the economy experiences minor contractions.
Official Responses and Industry Outlook
While representatives from the major automotive distributors have largely refrained from commenting on specific model performance, industry insiders suggest that a broader strategy shift is underway. A common theme in recent internal memos from major Japanese and European auto groups operating in Vietnam is the pivot toward "value-added ownership."

"The market is moving beyond just the purchase price," noted a senior consultant at an automotive market research firm in Ho Chi Minh City. "Customers are looking at the total cost of ownership, including the residual value of the car after five years. For some of these lower-selling models, the perception of value is being questioned by the consumer, and that is reflected in the sales charts."
Toyota’s official position remains focused on long-term sustainability. The company continues to prioritize the expansion of its hybrid vehicle portfolio, which has seen significantly better performance than their high-end gasoline-only counterparts. The concentration of their models on the "least sold" list is viewed by the company as a temporary adjustment period while they align their inventory with the evolving preferences of the Vietnamese middle and upper classes.

Broader Implications for the Vietnamese Auto Market
The situation in August 2026 serves as a bellwether for the rest of the year. The transition toward electrification and the demand for more technologically advanced vehicles are no longer future projections—they are current market realities. Brands that fail to adapt their premium offerings to these demands will likely see their inventory languish, regardless of the brand’s historical reputation.
Furthermore, the data underscores the importance of the Vietnamese consumer’s sensitivity to pricing. Even in the luxury segment, the "price-to-feature" ratio remains a critical factor. As the market becomes more transparent due to digital tools and increased access to global reviews, the era of relying solely on brand heritage to drive sales of high-priced, low-feature vehicles is coming to an end.
Strategic Recommendations for Stakeholders
For automotive manufacturers, the implications are clear:
- Inventory Optimization: There is a need to better balance stock levels for premium imports to avoid the accumulation of unsold units.
- Technological Integration: Investing in localizing software, navigation, and entertainment systems that cater to Vietnamese users will be crucial for maintaining competitiveness against emerging rivals.
- Incentivization: Short-term promotional campaigns are unlikely to resolve the structural issues behind low sales. A more effective strategy involves long-term financing solutions that lower the barrier to entry for prospective buyers.
In conclusion, the August 2026 sales figures are not necessarily a sign of a failing market, but rather an indication of a maturing one. Consumers are becoming more discerning, and manufacturers are being challenged to provide not just a machine, but a complete ecosystem of value, reliability, and modern prestige. As the industry moves toward the final quarter of the year, all eyes will be on how these brands adjust their portfolios to recover from the current slump and capture the year-end surge in demand. The dominance of Japanese brands in the bottom ten is a wake-up call that the status quo is shifting, and the race to define the future of the Vietnamese automotive landscape is accelerating.