Debate Erupts Over Proposed Ban On Transferring Future Housing Contracts And Its Potential Impact On Property Markets And Homebuyers

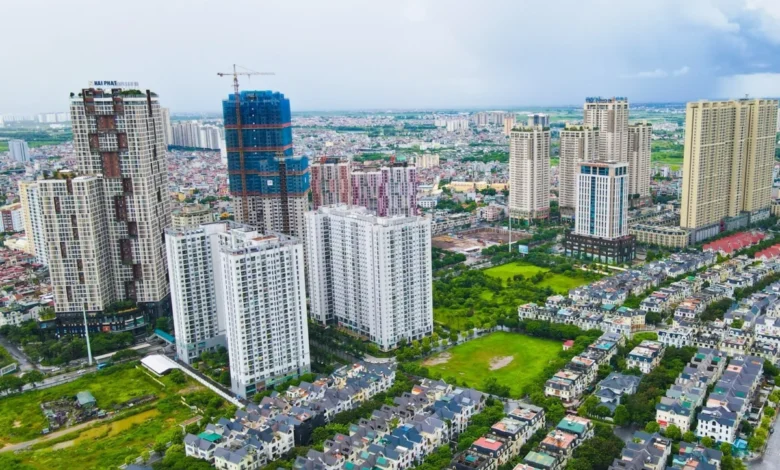
The debate surrounding Vietnam’s real estate regulatory framework has intensified following legislative discussions regarding potential restrictions on the transfer of future housing contracts. While policymakers aim to curb speculative bubbles and protect consumers from market volatility, legal experts and economic analysts have raised significant concerns. Critics argue that an absolute ban could inadvertently infringe upon citizens’ property rights, restrict legitimate liquidity, and drive high-risk transactions into unregulated informal markets, ultimately disrupting housing supply and pricing dynamics.
Legislative Background and the Core Controversy
The controversy centers on proposals discussed during parliamentary sessions regarding the Law on Real Estate Business (Amended). Lawmakers weighed measures that would prohibit the transfer of purchase and sale contracts for real estate properties still under construction—often referred to as future-formed housing. Alongside this, authorities explored transitioning toward a policy where developers could only sell residential units after construction is entirely completed.
Proponents of the strict measures argue that banning contract transfers and delaying sales until completion would eliminate speculative short-term flipping, a practice frequently blamed for artificial price inflation. However, economic and legal specialists caution that such sweeping restrictions fail to distinguish between malicious speculation and legitimate financial adjustments made by everyday homebuyers.
Legal Interpretations and Property Rights
Under the current legal framework, specifically the Law on Real Estate Business, future housing contracts are recognized as legal instruments that can be transferred under specific conditions. Legal professionals emphasize that purchasing a property under construction and subsequently transferring the contract represents a legitimate exercise of contractual rights and civil obligations, rather than an activity outside the scope of statutory regulation.
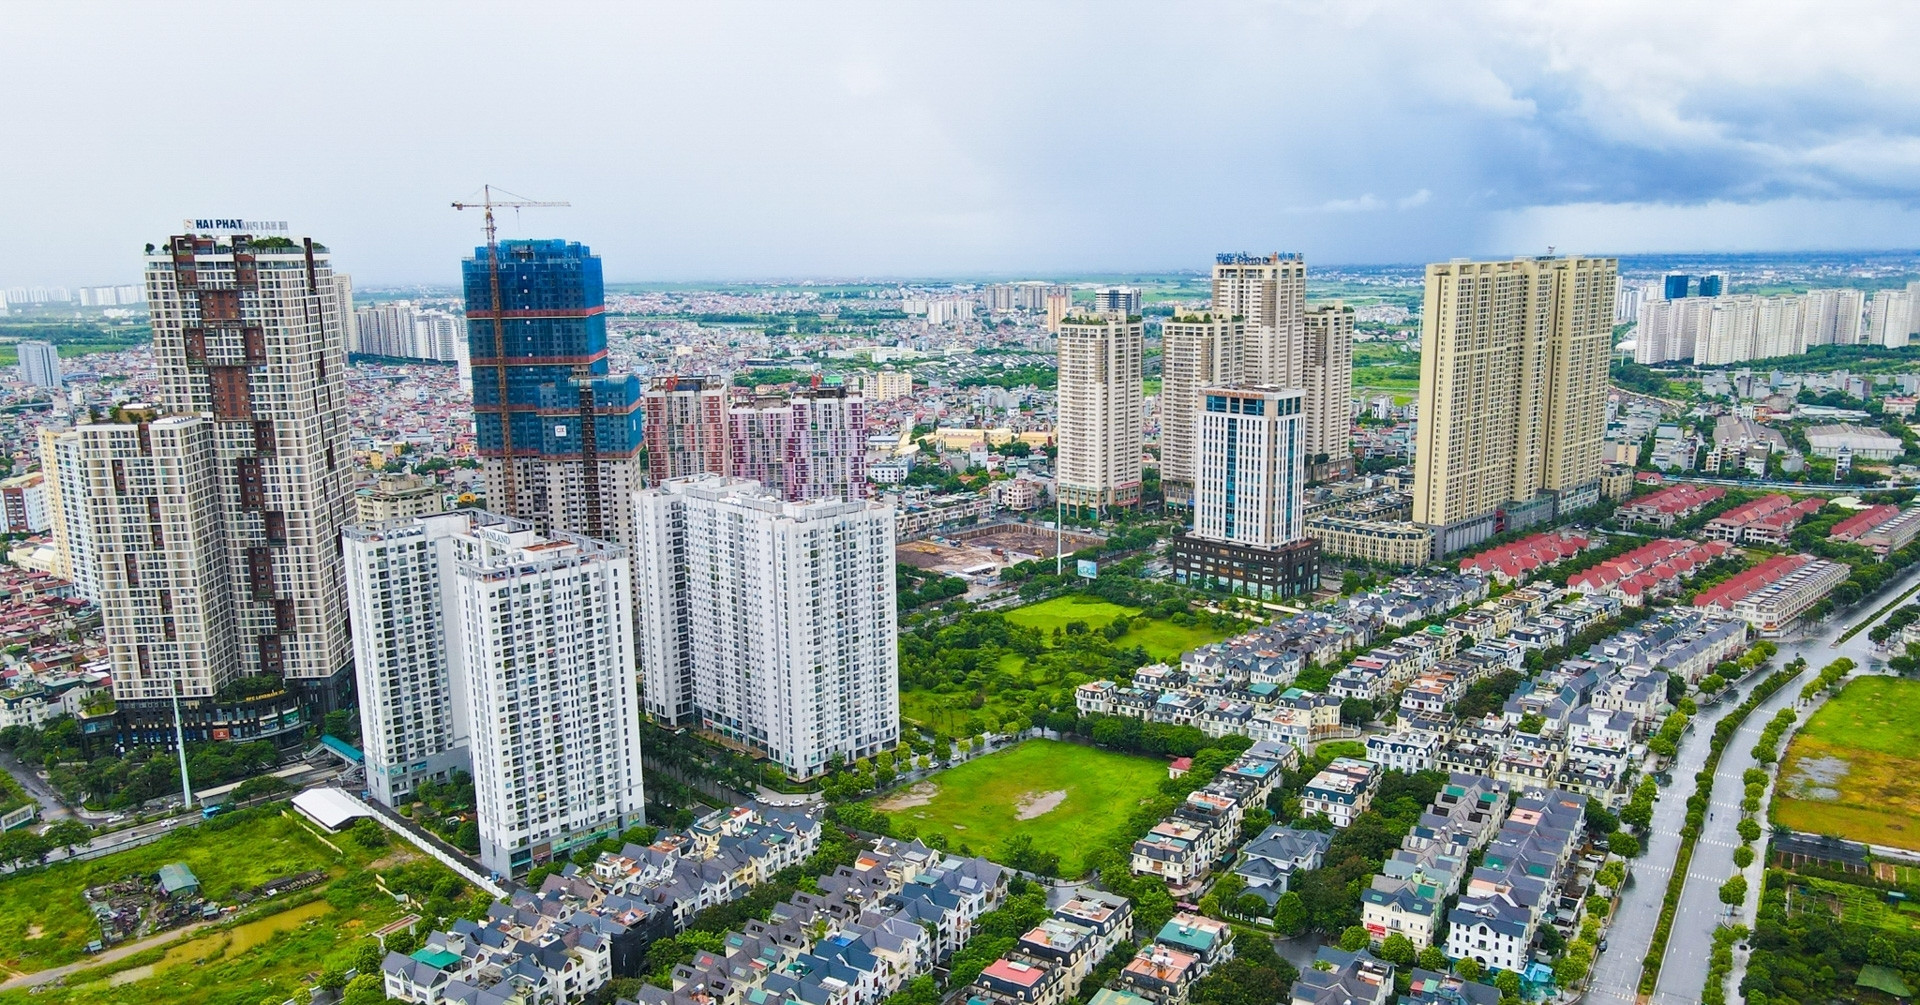
The right to transfer a contract serves as an essential financial safety valve for buyers. Households often encounter unforeseen economic hardships, changes in employment, or alterations in family circumstances that require them to liquidate assets. Prohibiting these transfers entirely could trap buyers who are no longer capable of meeting payment installments, thereby increasing their financial distress and exposing them to severe penalties or contract default. Furthermore, constitutional protections guarantee the right to private property and economic freedom, meaning any restrictions placed on contractual transfers must be proportionate and carefully targeted to avoid violating fundamental civil rights.
Economic Mechanics of Speculation and Market Distortion
Speculation in the pre-construction market typically relies on progressive payment schedules. Investors can secure the rights to a property by paying only an initial percentage of the total value during the early stages of development. When market prices rise, these investors can transfer their contracts for a profit margin without ever paying the full purchase price.
For instance, a buyer might commit to an apartment valued at 3 billion VND by initially paying 900 million VND. If market demand surges, the contract can be transferred to a secondary buyer with an added profit margin. If this cycle repeats multiple times among speculators, transaction prices detach entirely from underlying utility values and the real income levels of end-users, pricing genuine homebuyers out of the market.
Despite these risks, experts point out that contract transfers are merely one tool utilized by speculators rather than the root cause of property price inflation. Broader economic factors—such as land acquisition costs, construction material prices, credit availability, municipal infrastructure development, and overall housing supply constraints—play a more definitive role in determining market prices. Restricting contract transfers without addressing these foundational issues risks failing to control housing costs while creating secondary systemic vulnerabilities.
Risks of Informal Markets and Shadow Transactions
A primary warning issued by legal advisors is that an absolute ban on future contract transfers will not eradicate speculation; instead, it will drive speculative activity underground. When formal channels are closed, market participants frequently resort to unofficial mechanisms, such as irrevocable powers of attorney, complex deposit agreements, and private civil contracts designed to conceal the transfer of economic benefits.
Such informal transactions severely elevate legal risks for ultimate buyers. Without transparent state oversight or clear legal recourse, participants in the shadow market face heightened probabilities of contract disputes, fraud, and unverified encumbrances. Consequently, consumer protection diminishes precisely because transactions occur outside statutory enforcement frameworks.
Impacts on Market Liquidity, Developer Financing, and Housing Supply
Beyond consumer contracts, restrictive policies threaten the operational stability of real estate developers, particularly small and medium-sized enterprises. Real estate is a capital-intensive sector characterized by extended development cycles and slow capital recovery. Pre-sales of future-formed housing provide crucial liquidity that enables developers to fund construction milestones.
If developers are legally barred from selling properties until construction is fully completed, capital access will tighten drastically. Smaller firms may struggle to secure alternative financing, leading to a significant contraction in housing supply, particularly within the affordable housing segment. Ultimately, reduced supply combined with higher borrowing costs for developers will translate into higher end-consumer prices, defeating the original objective of making housing more accessible.
Expert Recommendations for Balanced Regulation
Rather than implementing absolute bans, financial and legal analysts advocate for sophisticated, targeted regulatory interventions that balance market transparency with property rights protection. Key recommendations include:
- Enhanced Financial and Operational Monitoring: Authorities should rigorously assess the financial capacity of real estate developers, enforce stringent criteria for entering the market, and strengthen bank guarantee mechanisms for future housing projects.
- Transparent Cash-Flow Control: Implementing stricter banking oversight on customer payment accounts ensures that funds are utilized strictly for project development, minimizing the risk of project abandonment.
- Targeted Anti-Speculation Measures: Instead of blanket prohibitions, policymakers can introduce progressive short-term capital gains taxes or establish centralized real estate databases to track transaction history and real transfer values, thereby deterring rapid flipping without harming genuine buyers.
- Flexible Transition Policies: Encouraging post-completion sales only for projects with robust financial backing, while allowing pre-construction sales under strict compliance conditions, prevents liquidity shocks across the broader economy.
Conclusion
The ongoing legislative review of the real estate framework highlights the complex challenge of balancing market stability with economic freedom. While protecting consumers from speculative excesses and fraudulent practices remains a vital national priority, regulatory policies must avoid stifling market liquidity or infringing upon legitimate property rights. A nuanced approach that focuses on financial transparency, robust developer accountability, and fair consumer safeguards will best serve the long-term goal of fostering an equitable, sustainable, and transparent housing market.