Government Extends Preferential Import Tariffs, Environmental Protection Taxes, and VAT Reductions for Petroleum and Jet Fuel Through End of 2026


In a decisive move aimed at stabilizing the domestic energy market and curbing inflationary pressures, the Vietnamese Government has officially issued Resolution 43, extending the preferential treatment on import tariffs, environmental protection taxes, and value-added taxes (VAT) for crude oil, petroleum products, production inputs, and jet fuel. This critical legislative intervention, signed into law on September 30, is designed to buffer businesses and everyday consumers against persistent global energy volatility, escalating geopolitical tensions in the Middle East, and domestic price fluctuations that have threatened broader economic growth.
The newly promulgated resolution mandates the continuation of targeted tax reductions previously outlined in Resolution 25, dated April 30, and Resolution 72, dated March 9. By extending these fiscal support mechanisms through December 31, 2026, the administration seeks to maintain a steady macroeconomic environment, ensuring that manufacturing sectors, transport companies, and airline operators can navigate mounting operational hurdles without transferring exorbitant costs down to the ultimate consumer.
Strategic Extension of Fiscal Relief
The continuation of these tax and tariff cuts underscores the government’s proactive stance on energy security and macroeconomic resilience. Under the framework of Resolution 43, preferential import duties, environmental protection levies, and VAT rates for gasoline, diesel, fuel oils, raw materials essential for domestic petroleum manufacturing, and aviation fuel will remain at a baseline of zero or at their previously reduced minimum thresholds.
Specifically, the special consumption tax on gasoline products will continue to be administered in accordance with the Law on Special Consumption Tax No. 66/2025/QH15 alongside its corresponding implementation guidelines. Under these established parameters, standard consumption tax rates are fixed at 10% for mineral gasoline, 8% for E5 biofuel, and 7% for E10 biofuel, maintaining a favorable tax differential that encourages the consumption of environmentally cleaner alternative fuels.
Economic analysts view the decision to maintain these reductions as a vital lifeline for a domestic economy striving to meet ambitious growth targets amidst external headwinds. Energy costs serve as a foundational input for virtually every sector of commerce; therefore, unchecked spikes in fuel prices inevitably trigger a cascading effect that drives up the cost of logistics, agricultural production, construction, and retail goods. By locking in these tax reliefs through the final quarter of 2026, policymakers have provided businesses with a predictable fiscal horizon, mitigating the risk of sudden cost shocks.
Escalating Global Tensions and Domestic Price Pressures
The necessity for Resolution 43 became acutely apparent as domestic fuel prices climbed steadily throughout August and September. Driven largely by protracted geopolitical instability and supply chain disruptions originating in the Middle East, international crude benchmarks experienced significant volatility, directly translating into higher pump prices across Vietnam.
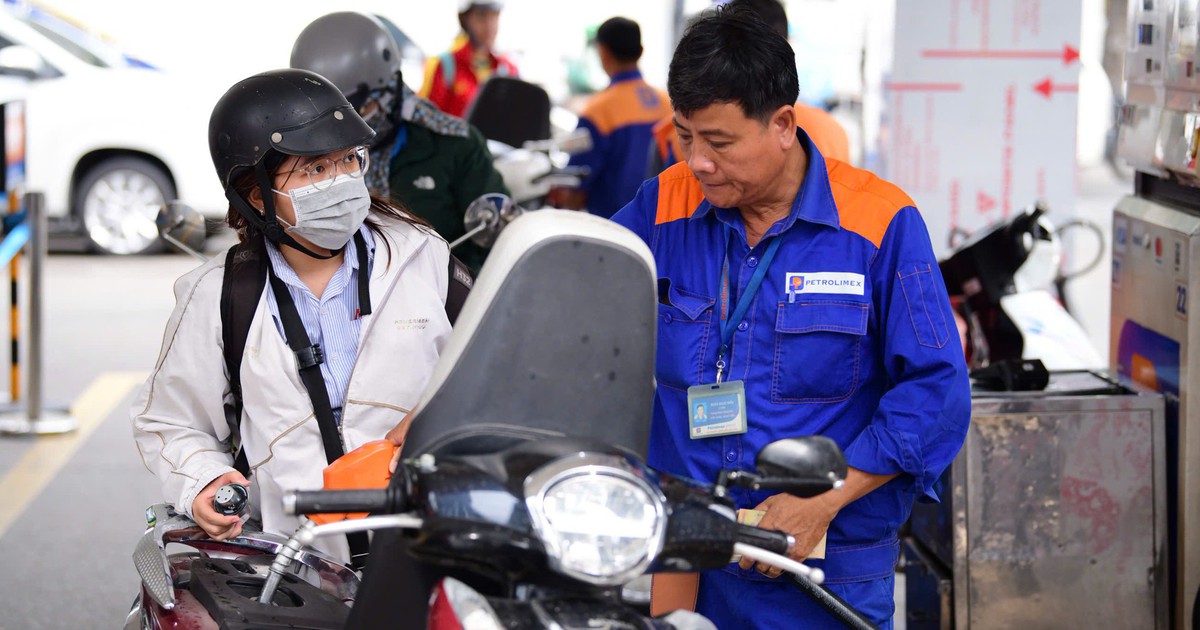
According to the joint administrative adjustments managed by the Ministry of Industry and Trade and the Ministry of Finance, retail prices reached notable highs during the late-September pricing cycle. E5RON92 gasoline climbed to 26,397 VND per liter following an increase of 1,258 VND, while E10RON95-III surged to 27,087 VND per liter after a markup of 1,451 VND. Concurrently, diesel 0.05S rose by 552 VND to settle at 30,497 VND per liter, and mazut 180CST 3.5S increased by 276 VND, capping prices at no higher than 19,472 VND per kilogram.
These adjustments represented some of the steepest upward revisions recorded over a three-month span, placing immense pressure on both retail consumers and commercial fleet operators. Furthermore, the operational capacity of the National Price Stabilization Fund has faced severe constraints. In many instances, the fund has been largely depleted or forced into a net-negative accounting balance across multiple petroleum trading enterprises due to prolonged deployment to cushion domestic price shocks without immediate state replenishment.
Navigating Market Volatility
Market observers note that international oil benchmarks have fluctuated widely over the past several weeks, alternating between periods of temporary relief—with some contracts dipping below the psychological threshold of $100 per barrel—and sudden bullish reversals driven by supply anxieties. This unpredictable trading environment continues to complicate domestic price management, making targeted fiscal policy interventions such as Resolution 43 indispensable.
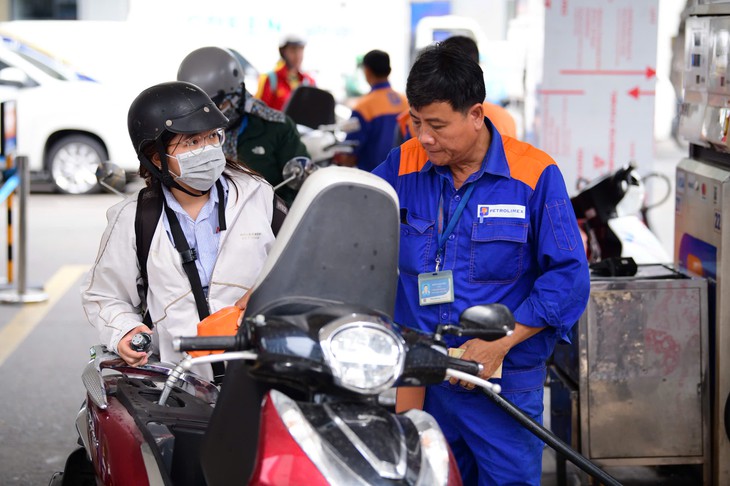
Recognizing the delicate balance required to maintain market equilibrium, regulatory bodies retain the flexibility to propose further adjustments should macroeconomic conditions deteriorate. The resolution explicitly stipulates that if global market developments necessitate more aggressive interventions—such as deeper budgetary withdrawals or further extensions of tax validity periods to safeguard energy security and market stability—relevant ministries are authorized to act. Specifically, the Ministry of Industry and Trade is empowered to submit formal recommendations to the Ministry of Finance, which in turn will petition the government for timely executive decisions.
Implications for Businesses and Consumers
The immediate impact of Resolution 43 is expected to be felt most acutely by the transportation, logistics, and aviation sectors, which count fuel among their primary variable operational expenditures. Airlines grappling with high jet fuel costs, alongside trucking and shipping firms facing narrow profit margins, will benefit significantly from the extension of zero-rated or minimized tax structures.
For the average citizen, the measure prevents a steeper compounding of inflation, shielding household purchasing power from the worst effects of global commodity shocks. While retail fuel prices will continue to reflect international market trends under the periodic pricing formulas, the absence of additional tax burdens prevents prices from scaling even higher peaks.
As Vietnam continues its post-pandemic economic consolidation, the administration’s measured fiscal interventions demonstrate an ongoing commitment to balancing state budgetary prudence with necessary socio-economic support. By keeping energy taxation minimized through the end of 2026, the government has established a predictable framework designed to foster sustained industrial output, curb inflationary momentum, and protect vulnerable consumer segments against external economic shocks.
Related posts: