The Federal Reserve has officially ended a long-standing pause in its monetary tightening cycle, announcing a 25-basis-point interest rate hike that elevates the benchmark federal funds rate to a range of 3.75% to 4%. This decision, finalized on September 16 following a two-day policy meeting, marks the first time the U.S. central bank has increased borrowing costs since July 2023, signaling a decisive shift in its strategy to combat persistent inflationary pressures that have remained stubbornly above the bank’s long-term 2% target.
The Rationale Behind the Hike
The decision to resume interest rate increases comes as a response to economic data that has defied earlier expectations of a cooling economy. In its post-meeting statement, the Federal Open Market Committee (FOMC) highlighted that domestic spending remains remarkably resilient, supported by robust business investment and a labor market that has shown little signs of significant slack.
However, the primary driver for this pivot is the re-acceleration of inflation. Despite six previous rate cuts totaling 175 basis points since July 2023, the Consumer Price Index (CPI) and the Fed’s preferred gauge, the Personal Consumption Expenditures (PCE) price index, have failed to anchor at the desired 2% level. Projections now suggest that inflation may not return to the target until 2029, a year later than previously estimated by Fed economists.
The global geopolitical climate has further complicated the Fed’s task. Escalating tensions in the Middle East have pushed crude oil prices above the $100-per-barrel threshold, injecting new volatility into energy markets and threatening to undo progress made in moderating core inflation.
A Chronology of Recent Monetary Policy
To understand the gravity of this shift, one must look at the trajectory of U.S. monetary policy over the past few years. Following the aggressive tightening cycle that began in the post-pandemic era, the Federal Reserve had entered a period of cautious easing.
- July 2023: The last major rate increase occurred, setting the stage for a period of high-interest rates designed to quell the post-COVID inflation spike.
- Late 2023 – Early 2024: The Fed began a series of six incremental rate cuts, hoping that the labor market would soften sufficiently to allow for a "soft landing."
- August 2024: Economic data revealed that inflation had not "cooled" as anticipated, leading to heightened anxiety among policymakers regarding the durability of price stability.
- September 16, 2024: The FOMC formally abandoned the easing path, opting for a 25-basis-point hike to reassert control over the inflationary cycle.
Official Stance and Policymaker Perspectives
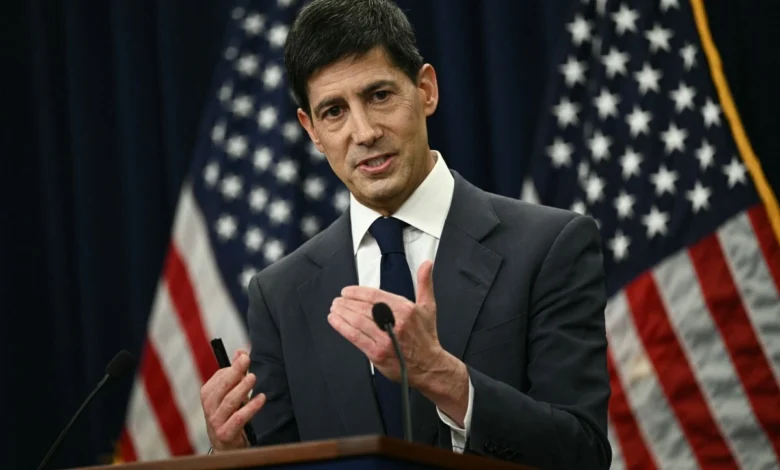
During the press conference following the announcement, Federal Reserve official Kevin Warsh emphasized the gravity of the current situation. "Our primary focus remains on price stability," Warsh stated. "It is clear that inflation has remained at an uncomfortably high level for an extended period, and we must act to ensure that expectations of future price increases do not become unmoored."
When questioned about whether the Fed could adopt a more surgical approach to address supply-side shocks—such as those in energy and food—Warsh was clear about the limitations of monetary policy. "We cannot influence the price of every individual commodity, whether it be oil or groceries at the supermarket," he noted. "But what we can and will do is ensure that any price volatility does not spread to the wider economy, preventing second- and third-round effects."
Addressing concerns about the central bank’s independence amidst political pressure, Warsh underscored that the Fed’s mandate is strictly defined. "A portion of our independence is our ability to focus solely on our defined mission," he added, noting that the bank remains focused on the structural health of the economy rather than short-term political cycles.
Economic Forecasts and Market Reactions
The Fed’s updated economic projections reflect a more hawkish outlook. The U.S. economy is now expected to grow by 2.3% for the current year, a slight upward revision from the June forecast. Furthermore, the unemployment rate is projected to settle near 4.1% by the end of next year.
The markets reacted with a mix of volatility and resignation. While interest rate hikes traditionally dampen equity valuations, the decision was largely priced in by investors following the release of recent, hotter-than-expected inflation reports. The S&P 500 managed a modest gain of 0.3% following the announcement, while the Nasdaq Composite rose 0.7%, bolstered by a recovery in artificial intelligence-related stocks. Conversely, gold prices faced downward pressure, sliding over $40 to $4,314 per ounce, as investors pivoted toward higher-yielding assets.
Political Implications and the "Midterm" Context
The timing of this hike is particularly sensitive, occurring less than two months before the U.S. midterm elections. The Republican Party, under the influence of former President Donald Trump, has framed the current economic environment as a failure of the incumbent administration.
The political stakes are high. With gasoline prices having risen more than 30% compared to the previous year and mortgage rates climbing consistently throughout the year, the "cost-of-living crisis" has become a central campaign issue. The Federal Reserve’s decision to tighten policy may further exacerbate these pressures in the short term, creating a challenging backdrop for the current administration as they seek to maintain control of Congress.
Broader Macroeconomic Implications
The decision to hike rates signals that the "higher-for-longer" narrative is officially back on the table. For businesses, this means that the cost of capital—already high—will remain a significant hurdle for expansion and capital expenditure. Companies that rely on debt financing to fuel growth will likely see their margins squeezed, potentially leading to a deceleration in corporate investment.
For the consumer, the implications are equally profound. High-interest rates will continue to keep borrowing costs for credit cards, auto loans, and personal credit elevated. The Federal Reserve is essentially signaling that it is willing to accept a period of slower economic growth and tighter financial conditions if it is the price required to prevent long-term inflationary damage.
Economists are now closely watching the bond market. While some have suggested that rising Treasury yields reflect a loss of faith in the central bank, officials maintain that the increase in borrowing costs is a logical outcome of a resilient economy where competition for capital is intensifying. As the Fed moves forward, the primary concern for the global financial system will be whether this tightening cycle can be executed without triggering a broader contraction or a significant disruption in global supply chains.
Conclusion: The Path Forward
The Federal Reserve’s pivot to a 25-basis-point hike serves as a stark reminder that the battle against inflation is far from over. By opting to raise rates, the central bank is prioritizing long-term stability over short-term economic comfort. As the U.S. enters a period of political uncertainty and global market volatility, the Fed’s ability to navigate these competing pressures will define the economic trajectory for the remainder of the decade. The focus now shifts to the next policy meeting, where investors will be looking for further clues on whether this hike is a singular response or the beginning of a new, sustained cycle of monetary tightening.