Global Economic Resilience Faces Emerging Risks Amid Shifting Credit Landscapes and Artificial Intelligence Volatility

The global economy is currently navigating a period of complex transition, characterized by a surprising degree of resilience in credit markets and macroeconomic indicators, yet tempered by a rising tide of systemic risks. According to the latest comprehensive risk assessment report for the fourth quarter of 2026 and the 2027 outlook published by Fitch Ratings, the international financial landscape remains in a state of delicate equilibrium. While sovereign and corporate credit profiles have largely maintained their integrity, analysts warn that the underlying volatility, particularly surrounding the rapid, capital-intensive expansion of Artificial Intelligence (AI), is beginning to cast a long shadow over global fiscal stability.
The Current State of Credit Markets: A Resilient Foundation
Contrary to fears of a widespread credit crunch, the global credit environment has displayed remarkable durability throughout 2026. Data from Fitch Ratings indicates that the number of credit upgrades has consistently outpaced downgrades across their global portfolio, even when accounting for the heightened scrutiny applied to European banking institutions following recent regulatory recalibrations.
This stability is largely attributed to a robust underlying demand for capital and a steady, albeit cautious, recovery in global GDP growth, which has been revised upward to 2.6% for the 2026 fiscal year. The Eurozone, once considered the primary candidate for a prolonged stagnation, has demonstrated a capacity for adaptation that has outperformed initial projections.
In the United States, corporate bond issuance has reached record levels, signaling that businesses retain access to liquidity despite the lingering pressure of higher interest rates. The credit spread differentials—the gap between yields on riskier debt and safe-haven assets—remain near historical lows, though they experienced a slight, predictable widening during the third quarter of 2026. This trend suggests that investors remain broadly confident in the ability of corporations to meet their debt obligations, even in a high-interest-rate environment.
Chronology of Economic Shifts and Policy Responses
The trajectory of the 2026 economic landscape was defined by three distinct phases. During the first quarter, the focus remained on inflationary containment, with central banks across the G7 maintaining high, restrictive interest rates. By the second quarter, markets began to pivot toward the implications of AI-driven capital expenditure, which fueled a massive rally in equity markets, particularly in the technology sector.
By the third quarter of 2026, a shift in sentiment began to emerge. Investors started demanding higher premiums for debt funding large-scale AI projects, reflecting a nascent concern regarding the long-term profitability of these massive infrastructure investments. This period also saw the postponement of several major AI-focused Initial Public Offerings (IPOs), serving as a clear indicator of growing investor apprehension.
As we move toward 2027, the focus has shifted from mere growth to the sustainability of that growth. The "soft landing" narrative, which dominated the discourse for much of the year, is now being tested by the structural costs associated with the digital transformation of global industry.
The AI Paradox: From Growth Catalyst to Risk Factor
The most significant development in the current risk outlook is the dual role played by Artificial Intelligence. Initially viewed as the primary driver of productivity and economic expansion, AI has now moved to the center of financial risk analysis.
The scale of this shift is unprecedented. Estimates suggest that by 2027, capital expenditure specifically earmarked for AI infrastructure will reach $1 trillion—a fivefold increase compared to 2024. While this spending has bolstered economic figures in the short term, the concentration of such massive capital in a singular, unproven sector has created a concentration risk that rating agencies can no longer ignore.
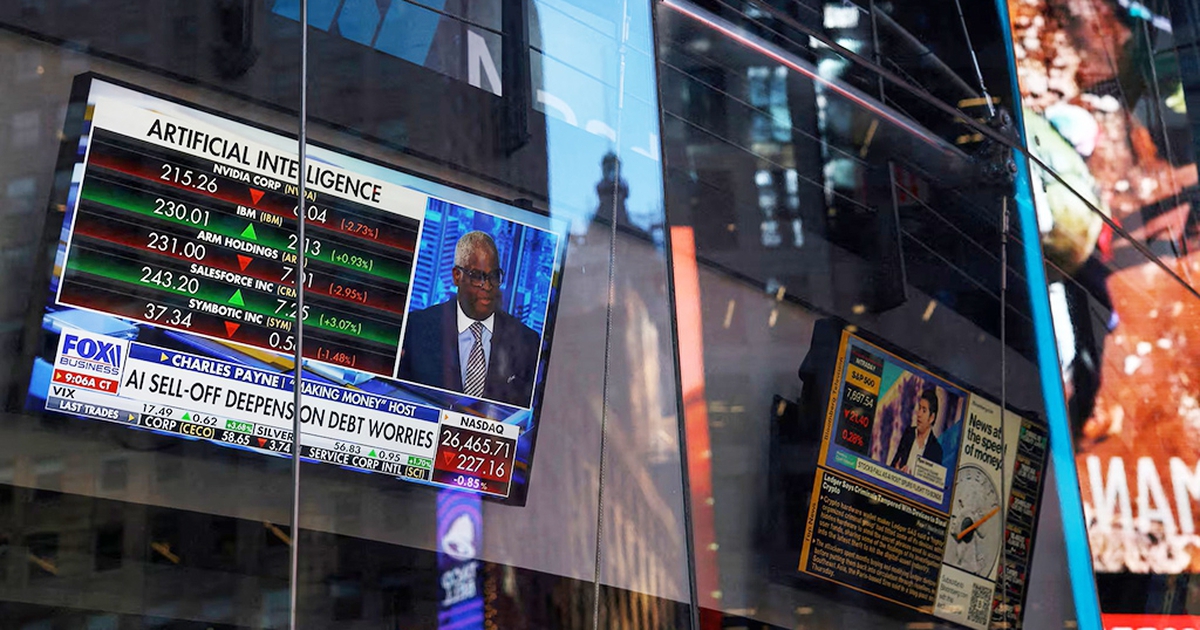
The economic concern is twofold: first, the "monetization gap," where the cost of developing and maintaining sophisticated AI models currently far outweighs the revenue generated; and second, the emergence of open-source models that offer comparable performance to proprietary systems at a fraction of the cost. This creates a hyper-competitive environment that threatens the margins of the very companies that have driven the recent stock market surge.
Shifting Geopolitical and Trade Perspectives
Interestingly, Fitch Ratings has opted to remove "trade instability and tariffs" from its primary list of top-tier risks for the coming year. While the potential for shifts in U.S. tariff policy remains, and ongoing trade negotiations between China and the European Union continue to be a source of friction, these factors are now viewed as secondary to the broader structural risks of credit and technology-led debt.
This change in perspective reflects a broader realization among market analysts: the global economy has effectively "priced in" a certain level of geopolitical fragmentation. Investors are no longer reacting with the same level of volatility to trade rhetoric as they were in previous cycles. Instead, the market is focusing its anxiety on the sustainability of corporate debt loads and the efficacy of the massive capital allocations toward emerging technologies.
Implications for Investors and Policymakers
The implications of this outlook are profound for both the private and public sectors. For investors, the era of "easy money" flowing into any AI-related venture is coming to a close. Institutional investors are increasingly demanding rigorous financial transparency and higher interest rates for loans associated with large-scale digital transformation projects.
For policymakers, the challenge is to balance the need for innovation-led growth with the need to prevent a bubble in the technology sector that could threaten broader financial stability. If the current trajectory of AI spending leads to a sudden market correction, the resulting "shock" could have a ripple effect on the banking sector, potentially leading to a broader economic downturn.
Data-Driven Analysis of Market Sentiments
The data suggests a cooling of the "AI fervor." Throughout the third quarter of 2026, the volume of high-yield debt issuance specifically for AI-related R&D saw a marked decline. Furthermore, surveys of institutional fund managers indicate that capital allocation strategies are shifting toward sectors with more predictable cash flows, such as infrastructure, energy, and defensive consumer goods.
Despite these concerns, the overall credit rating environment remains stable. The "investment grade" segment of the market continues to hold up well, and the "speculative grade" category has shown surprising resilience as companies have managed their balance sheets with a degree of discipline that was absent in previous credit cycles.
Looking Ahead to 2027
As the global economy enters 2027, the primary narrative will likely be the reconciliation between the promise of technological advancement and the reality of financial constraint. The resilience that has defined the 2026 economy is a testament to the strength of the current global financial architecture, but it is not a guarantee of future performance.
The path forward requires a focus on debt management and a more disciplined approach to capital expenditure. The "AI risk" is not necessarily a signal of an imminent crash, but rather an indication that the global economy is entering a more mature, discerning stage of its current cycle.
In conclusion, while the foundational elements of the global economy—sovereign credit, bank stability, and GDP growth—remain fundamentally sound, the transition to an AI-integrated industrial landscape introduces a new layer of systemic risk. The coming year will test whether the current generation of corporate and financial leaders can navigate this transition without triggering the very instability that market participants are currently hedging against. The vigilance shown by rating agencies like Fitch is a vital component of this transition, ensuring that the necessary risks are identified and managed before they evolve into systemic crises. As global markets look toward 2027, the emphasis will undoubtedly shift from growth at any cost to the long-term, sustainable generation of value in an increasingly complex and technologically driven world.