The Federal Reserve has decided to maintain its benchmark interest rate within the current range of 3.75% to 4%, a move that aligns with widespread market expectations following a period of intense deliberation among policymakers. On October 28, the Federal Open Market Committee (FOMC) concluded its two-day policy meeting, signaling a strategic pause in the monetary tightening cycle that saw the central bank initiate a rate hike just last month—its first such adjustment since July 2023.
This decision serves as a pivotal moment for the U.S. economy, as the Fed attempts to balance the delicate task of curbing persistent inflation while safeguarding a labor market that continues to show remarkable resilience. By holding rates steady, the central bank is effectively taking a "wait-and-see" approach, allowing the cumulative impact of previous policy shifts to permeate through the broader financial system before committing to further restrictive actions.
A Chronology of Recent Monetary Policy
The current trajectory of the Federal Reserve is best understood through the lens of its recent, aggressive pivot. For years, the U.S. economy benefited from an ultra-loose monetary policy designed to stimulate growth in the wake of global disruptions. However, as inflation began to climb, the FOMC shifted its focus toward price stability.
The cycle of interest rate hikes initiated in the late summer of 2023 marked the beginning of a new era of monetary policy. Following the September 2024 increase, analysts were divided on whether the Fed would sustain the momentum or take a brief hiatus. The October 28 decision clarifies that the committee is opting for a measured approach. According to official statements, the Fed is closely monitoring the "lag effect" of its policies—a phenomenon where interest rate changes take several months, or even quarters, to manifest fully in consumer spending and corporate investment data.
Economic Context and Official Perspectives
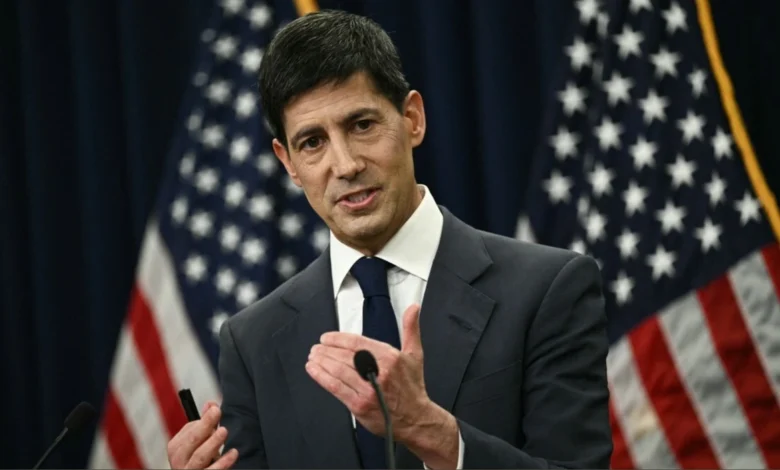
During the post-meeting press conference, Chairman Kevin Warsh acknowledged the mounting complexity of the economic landscape. While he noted that the labor market remains relatively robust—a point of contention for those fearing a recession—he did not shy away from the reality that inflation has remained stubbornly above the committee’s 2% target for nearly six years.
"We need more information to make informed decisions that align with our long-term goals," Warsh stated. "The committee is firmly committed to maintaining price stability, and our current strategy is designed to ensure that inflation returns to our target in a timely, sustainable manner."
Warsh also provided a glimpse into the internal operations of the Fed for the coming years. In an effort to streamline the policymaking process, the FOMC is considering reducing the number of meetings dedicated to interest rate decisions. By 2027, the committee expects to hold only one meeting focused specifically on long-term monetary strategy without a corresponding vote on rates. By 2028, the number of formal rate-setting meetings is expected to be reduced to six, reflecting a transition toward a more strategic, rather than reactionary, policy framework.
When pressed on why the committee chose to pause despite inflationary pressures, Warsh emphasized that inflation does not respond to a calendar. "Inflation is not tethered to a specific date or a single data point," he explained. "Our mandate is broader than that. We are observing that expectations have shifted in a more positive direction since our last meeting, which provides us with the confidence to pause."

Internal Dissent and Market Reaction
The decision to hold rates was not unanimous. Two high-ranking officials expressed dissent, advocating for a 25-basis-point increase. Board of Governors member Lisa Cook and Cleveland Fed President Beth Hammack both voted against the majority, suggesting that the current inflationary environment warrants further tightening to ensure the central bank does not fall behind the curve.
The financial markets reacted to the news with a mixed performance, reflecting the uncertainty inherent in the current climate. Following the announcement, the Nasdaq Composite saw a minor decline of 0.13%, while the S&P 500 and the Dow Jones Industrial Average (DJIA) experienced modest gains. The Dollar Index remained largely unchanged, suggesting that the markets had already priced in the pause. Meanwhile, gold prices witnessed a sharp decline, shedding more than $20 per ounce to settle at $4,035, as investors recalibrated their portfolios in response to the Fed’s signaling of a longer-term, "higher-for-longer" interest rate environment.
Implications for the Broader Economy
The implications of the Fed’s stance extend far beyond Wall Street. For American households, the pause offers a temporary reprieve from the rapid increase in borrowing costs, which have impacted everything from mortgage rates to credit card interest and auto loans. However, the underlying issue of high prices remains a significant burden.
For the corporate sector, the environment remains challenging. Businesses that have become accustomed to cheap capital are now operating in a world where the cost of debt is significantly higher. Analysts are now looking toward the upcoming midterm elections, where the control of the House and Senate will play a critical role in shaping the fiscal policy that runs parallel to the Fed’s monetary policy.
The interaction between the Republican Party’s platform—led by the influence of former President Donald Trump—and the Fed’s mandate has become a subject of intense political and economic debate. If the government pursues expansionary fiscal policies, the Fed may find itself in the difficult position of having to tighten monetary policy even further to prevent an inflationary spiral, thereby potentially stifling economic growth.
Looking Ahead: The Path to 2%
The primary focus for the Federal Reserve remains the elusive 2% inflation target. While the recent data shows some softening in consumer price indices, the persistence of energy costs and service-sector inflation continues to pose a threat. The committee has transitioned its assessment of the U.S. economy from "stable" to "strong," acknowledging that investment remains high and job creation continues to track alongside labor force growth.
Despite this optimism, the path forward is fraught with uncertainty. The Fed has signaled that it may resume rate hikes as early as December, depending on incoming data regarding employment, consumer sentiment, and supply chain health. For now, the central bank is playing a game of patience, betting that the current interest rate levels are sufficiently restrictive to bring inflation under control without inducing a significant economic contraction.
As the year draws to a close, the focus for both policymakers and investors will shift toward the fourth-quarter economic reports. These will provide the necessary evidence to determine whether the "pause" was a prudent strategic delay or a missed opportunity to anchor inflation expectations more firmly. One thing is certain: the Federal Reserve’s role as the guardian of the U.S. economy has never been more scrutinized, and its next move will be defined by its ability to navigate a landscape where every decision carries significant weight for the global financial order.
The Federal Reserve’s current mandate is a testament to the challenges of modern economic management. With the labor market still showing signs of strength and inflation proving to be a persistent adversary, the central bank’s ability to remain data-dependent while communicating clearly with the markets will be the ultimate test of its efficacy in the coming months. As Chairman Warsh noted, the committee remains "cautiously optimistic," but the margin for error remains razor-thin. For now, the markets—and the American public—will continue to wait for the next chapter in this unfolding economic narrative.