Digital Payment Ecosystems Drive Financial Inclusion and Economic Transformation in Vietnam

The rapid acceleration of digital payment adoption in Vietnam has transcended mere convenience, emerging as a foundational pillar for financial inclusion, enterprise modernization, and the broader development of a digital economy and society. Data released by the State Bank of Vietnam (SBV) for the first eight months of 2026 reveals a robust upward trajectory in non-cash transactions, which surged by more than 34% compared to the same period in the previous year. This shift reflects a systemic transition in consumer behavior and a deepening of the national digital infrastructure.
The Quantitative Surge: A Snapshot of 2026
The figures provided by the central bank underscore a profound transformation in how Vietnam’s population interacts with financial services. During the first eight months of 2026, transactions conducted via the internet reached over 4.4 billion, totaling a value of 81.1 quadrillion VND. This represents a significant year-on-year increase of 46.57% in volume and 21.77% in value, illustrating that both the frequency and the scale of digital financial engagement are rising in tandem.
Mobile banking, arguably the most accessible gateway to digital finance for the average citizen, demonstrated even more dramatic adoption rates. Mobile-based transactions hit 14 billion in volume, with a total value of 58.4 quadrillion VND. While the volume increased by a staggering 35.33%, the transaction value saw a more modest growth of 2.39%, suggesting that while the public is increasingly using mobile apps for frequent, lower-value daily payments, the technology has become deeply embedded in the micro-transactions of the everyday economy.
One of the most notable contributors to this shift is the widespread adoption of QR code payments. In the monitored period, QR payments accounted for 311 million transactions with a value of 274.2 trillion VND. Compared to the same period in 2025, the volume of these transactions grew by 6.66%, while the value climbed by 25.85%. This discrepancy indicates that consumers and merchants are moving away from cash for larger, more significant purchases, trusting the security and efficiency of QR-based infrastructure.
Sóng Festival: A Milestone in Digital Normalization
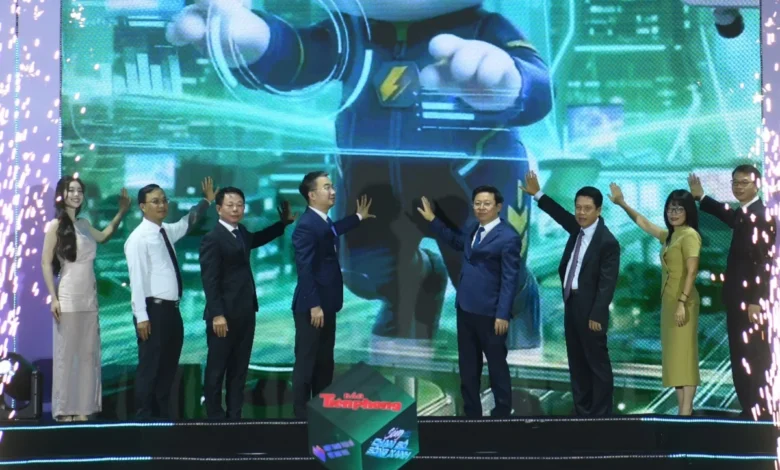
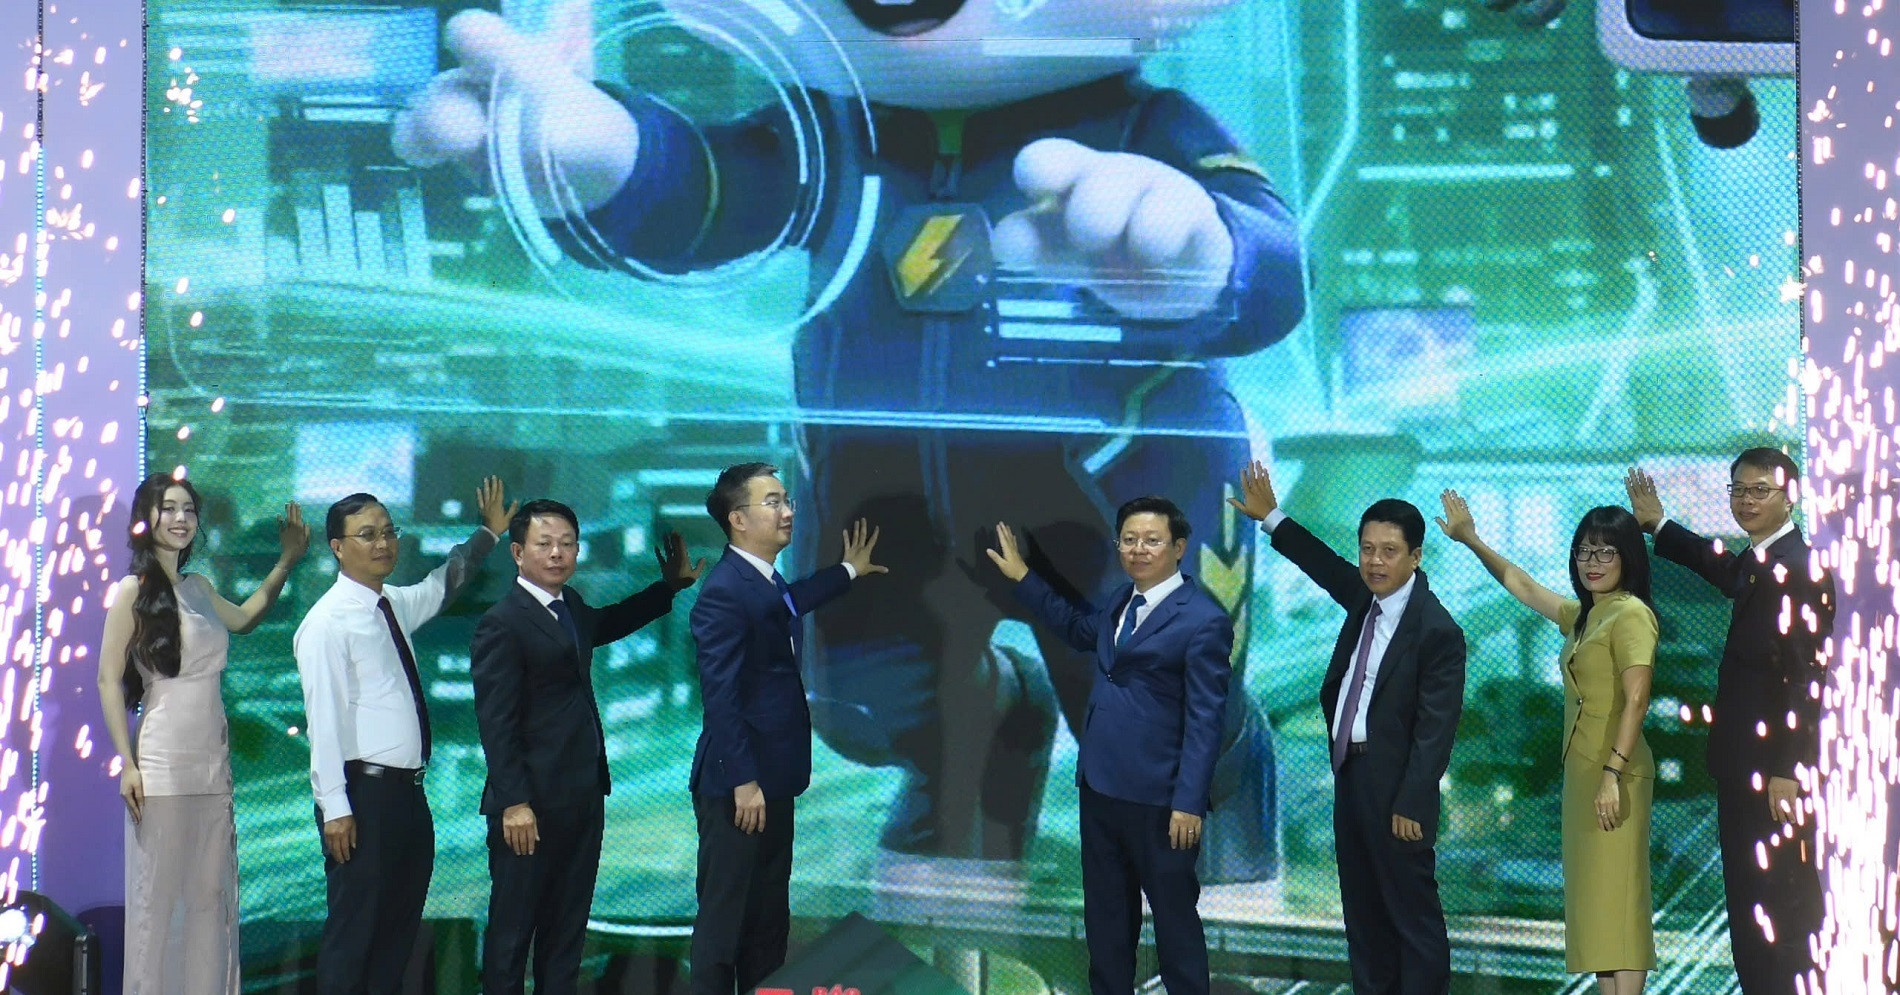
This digital evolution was celebrated and showcased during the Sóng Festival, held on October 24, 2026, at the Trần Nhân Tông pedestrian street in Hanoi. As a flagship event under the sixth annual Vietnam Digital Payment Day—organized by Tiền Phong Newspaper in coordination with the National Payment Corporation of Vietnam (NAPAS) and under the guidance of the State Bank of Vietnam—the festival served as a microcosm of the nation’s cashless future.
The event acted as a practical demonstration of a frictionless economy. Across the two-day festival, 100% of transactions at the nearly 70 booths—ranging from culinary arts and consumer goods to fashion, technology, and education—were conducted exclusively through digital means. Attendees utilized cards, QR codes, e-wallets, and biometric authentication, effectively banning physical currency from the premises.
Strategic Perspectives on Digital Finance
During the opening ceremony, Phùng Công Sưởng, Editor-in-Chief of Tiền Phong Newspaper, highlighted the pervasive nature of digital payments in modern life. "From urban centers to rural villages, and from large retail chains to small-scale street vendors, modern payment methods such as cards, QR codes, e-wallets, and mobile payments are enabling us to conduct transactions more quickly, conveniently, and securely than ever before," Sưởng noted.
This sentiment was echoed by Nguyễn Quang Minh, General Director of NAPAS. According to Minh, the true value of the digital payment revolution extends beyond the mere speed of transactions. It serves as a vital bridge, allowing citizens and businesses, particularly those previously underserved by traditional banking, to access sophisticated financial services. This, in turn, fosters a more inclusive financial ecosystem and provides a robust framework for the development of a digital-first economy.
Cross-Border Implications and Future Connectivity
The scope of Vietnam’s digital payment ecosystem is no longer confined to national borders. The integration of domestic payment apps with regional networks has simplified cross-border commerce. Consumers can now scan QR codes on their familiar domestic apps to pay for services in various foreign countries, mirroring the ease of domestic transactions.
This interoperability is a critical development for local businesses and the tourism sector. By leveraging these technologies, small-scale enterprises and service providers gain the ability to interact with international customers at a fraction of the traditional cost, significantly lowering the barrier to entry for cross-border trade.
The Role of Infrastructure and Security
The success of these initiatives relies heavily on the underlying technical infrastructure and, perhaps more importantly, public trust. With over 31 banks, financial institutions, and international card organizations participating in the Sóng Festival, the collaborative effort between the public and private sectors is evident.
However, as the volume of digital transactions grows, so does the imperative for cybersecurity. The rise in digital payments has necessitated significant investments in fraud prevention, data protection, and biometric security. As noted in recent financial reports, banks are increasingly deploying advanced AI-driven security protocols to protect customer data, including fingerprints and facial recognition signatures, ensuring that the convenience of digital payments does not come at the expense of user safety.
Chronology of the Digital Shift
- Foundational Phase (2020-2022): Initial surge in digital adoption catalyzed by the global pandemic, which necessitated contactless interactions and accelerated the digitalization of retail banking.
- Infrastructure Scaling (2023-2024): Implementation of standardized QR codes (VietQR) and the expansion of the NAPAS inter-bank switching system, providing the necessary backend for mass adoption.
- Normalization Phase (2025-2026): Digital payments transition from a "novelty" to a standard operating procedure for the average consumer, evidenced by the 34% growth in non-cash transaction volumes in the current year.
- Integration and Beyond (Post-2026): Focus shifts toward international interoperability, the integration of advanced biometric verification, and the inclusion of micro-enterprises in rural provinces into the formal digital financial network.
Broader Economic Implications
The transition to a cashless society is a macroeconomic objective with far-reaching implications. By reducing reliance on cash, the government aims to increase the transparency of financial flows, reduce the costs associated with currency printing and management, and improve the speed of monetary policy transmission.
Furthermore, the data generated by these transactions provides a wealth of information that can be used to improve credit scoring for individuals and small businesses. In the traditional banking model, many citizens lacked the credit history required to secure loans. In the emerging digital model, transaction patterns, payment consistency, and digital footprint serve as alternative data points, allowing financial institutions to assess risk more accurately and extend credit to a broader segment of the population.
Conclusion
The data from 2026 confirms that Vietnam has moved beyond the early stages of digital adoption and is now in a phase of systemic maturity. The Sóng Festival and the sustained growth in transaction volumes demonstrate that the digital payment ecosystem is no longer just a technological project; it is a social and economic movement. As the nation continues to integrate these technologies into daily life, the focus will likely shift toward maintaining the security and stability of this vast network, ensuring that the promise of a digital economy remains accessible and safe for all citizens.
The commitment of both the State Bank of Vietnam and the private sector to fostering this growth signals a long-term strategic priority. With continued investment in infrastructure and a proactive approach to cybersecurity, the trajectory of digital payments in Vietnam is poised to remain a primary driver of national economic competitiveness for the foreseeable future.