VietinBank Launches Online Overdraft Product Secured by Online Deposits to Enhance Financial Flexibility

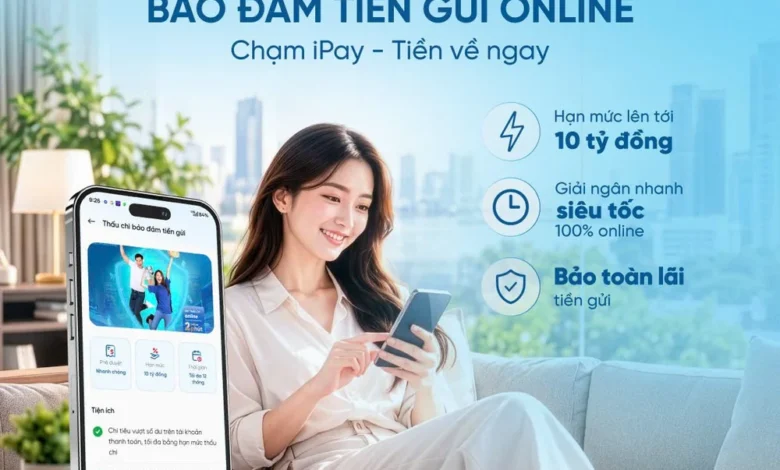
In a strategic move to optimize liquidity for individual customers, Vietnam Joint Stock Commercial Bank for Industry and Trade (VietinBank) has officially launched a new online overdraft facility secured by online savings deposits. This innovative financial product, accessible directly through the VietinBank iPay Mobile application, is designed to provide immediate access to capital for customers who hold term deposits that have not yet reached maturity. By offering a digital solution that allows users to leverage their existing savings as collateral without the need to liquidate their accounts prematurely, the bank is addressing a common financial dilemma faced by many retail investors.
The introduction of this product marks a significant milestone in VietinBank’s ongoing digital transformation strategy. As the financial sector in Vietnam shifts toward mobile-first banking experiences, this service empowers customers with greater control over their assets. Under the new program, eligible customers can secure an overdraft limit of up to 90% of their online deposit value, with a maximum cap of 10 billion VND. This mechanism ensures that depositors do not have to forfeit the interest rates accrued on their savings, providing a bridge between long-term investment goals and short-term liquidity needs.
Bridging the Gap: The Mechanics of Online Overdrafts
For years, customers requiring urgent funds before the maturity date of a savings account faced a difficult trade-off: they could either withdraw their funds early, thereby losing most or all of the interest earned, or look for alternative, often more expensive, borrowing options. VietinBank’s new product effectively eliminates this trade-off by allowing the deposit to serve as collateral while remaining active in the bank’s system.
The core advantage of this facility is the preservation of interest earnings. Because the deposit remains "locked" as a pledge for the overdraft, it continues to earn interest according to the original terms of the agreement. The customer effectively borrows against their own wealth, paying interest only on the amount actually utilized and for the specific duration of the usage, rather than on the entire approved overdraft limit. This "pay-for-what-you-use" model significantly lowers the cost of borrowing and enhances the overall efficiency of personal financial management.
Operational Parameters and Financial Flexibility
The product features a flexible structure tailored to the diverse needs of modern banking clients. The overdraft limit is determined based on the value of the online savings deposit, with the maximum term of the overdraft reaching up to 12 months. Crucially, the term of the overdraft cannot exceed the remaining maturity period of the underlying deposit, ensuring that the loan is intrinsically linked to the term of the collateral.
In terms of pricing, the interest rate for the overdraft is calculated as the interest rate of the underlying online deposit plus a margin. Currently, VietinBank has set this margin at 3.5% per annum. This competitive pricing structure is designed to be transparent, allowing users to calculate their potential costs easily via the mobile app. By decoupling the overdraft interest from the base savings rate and applying the margin only to the utilized portion, the bank provides a clear and predictable financial instrument for its users.
The Digital Integration Process
Integration with the VietinBank iPay Mobile application is central to the user experience. The process is entirely digitized, allowing for 24/7 access and immediate disbursement. Customers can navigate to the "Overdraft secured by online deposits" function within the app, input their desired loan amount, and submit the request.
Following the approval of the application—which is streamlined through the bank’s automated credit scoring systems—the customer completes the loan contract digitally. Authentication is handled through modern security protocols, including one-time passwords (OTP) or FacePay technology. Once confirmed, the credit line is available for immediate use, reflecting the bank’s commitment to providing seamless, frictionless digital banking services.
Eligibility and Risk Management
To maintain a high standard of asset quality, VietinBank has established specific eligibility criteria. The service is available to Vietnamese citizens aged 18 and older who possess full civil legal capacity. A critical requirement for approval is that the applicant must not have any outstanding debts classified as "Group 2" (special mention) or worse, nor any record of bad debt at VietinBank or any other credit institution.
Regarding the collateral, the product is limited to online savings deposits with a term of one month or longer, including savings where interest is paid at the end of the term or contracts opened directly via the VietinBank iPay platform. It is important to note that this specific product does not apply to accumulated savings products or those that allow for flexible partial withdrawals, as these products have different liquidity profiles that would complicate the collateralization process.
Broader Context: VietinBank’s Digital Evolution
The launch of this product is consistent with the broader strategic vision of VietinBank to become the most modern, efficient, and reliable commercial bank in Vietnam. As a national commercial bank, VietinBank plays a systemic role in the Vietnamese economy, and its shift toward a "digital-first" architecture is a central component of its long-term growth.
The banking industry in Vietnam has undergone a rapid transformation over the past five years. Driven by a young, tech-savvy population and a government push for a cashless society, banks have been forced to innovate or risk losing market share to fintech competitors. By embedding credit products directly into mobile applications, legacy banks like VietinBank are successfully competing by leveraging their large existing customer base and the trust associated with their brand.
Data from the State Bank of Vietnam indicates that the volume of non-cash payments and mobile banking transactions has seen double-digit growth annually. This transition is not merely about convenience; it is about data-driven financial inclusion. By offering instant credit based on real-time deposit data, banks can reduce the administrative burden on both the institution and the client, while simultaneously lowering the risk profile of the loan portfolio.
Implications for the Retail Banking Sector
The emergence of such products has profound implications for the retail banking sector. Firstly, it encourages higher levels of deposit mobilization. When customers know they can access their money in an emergency without penalty, they are more likely to commit their savings to longer-term, higher-interest accounts. This stability is beneficial for the bank’s liquidity management.
Secondly, it changes the relationship between the consumer and the bank. Banking is no longer a transactional event that occurs within the walls of a physical branch; it is an integrated part of the customer’s daily digital life. By offering 24/7 lending, VietinBank is positioning itself as a partner in the customer’s financial journey, capable of providing support exactly when it is needed.
Finally, the focus on automated, algorithm-based credit assessment suggests that the role of human bank tellers and loan officers is shifting. While face-to-face consultation remains available at branches for complex financial needs, the bulk of routine retail lending is increasingly handled by sophisticated software. This allows banks to allocate human resources to more value-added advisory roles while keeping operational costs low.
Conclusion and Future Outlook
As VietinBank continues to scale its digital services, the introduction of this secured overdraft product serves as a case study in how established financial institutions can modernize their offerings to meet contemporary demands. By providing a safe, transparent, and highly accessible way for customers to manage their liquidity, the bank is reinforcing its reputation for reliability while simultaneously driving its digital agenda.
For customers, the message is clear: personal wealth management is becoming more flexible and responsive to the realities of the modern economy. Those interested in the service are encouraged to explore the features within the iPay Mobile app or contact the nearest branch for personalized consultations. With a dedicated support hotline (1900 558 868) and a robust digital infrastructure, VietinBank is setting a new benchmark for how commercial banks in Vietnam serve the retail segment in the digital age. As the financial landscape continues to evolve, the success of such products will likely encourage further innovation, ultimately benefiting the consumer with more options, lower costs, and greater financial empowerment.