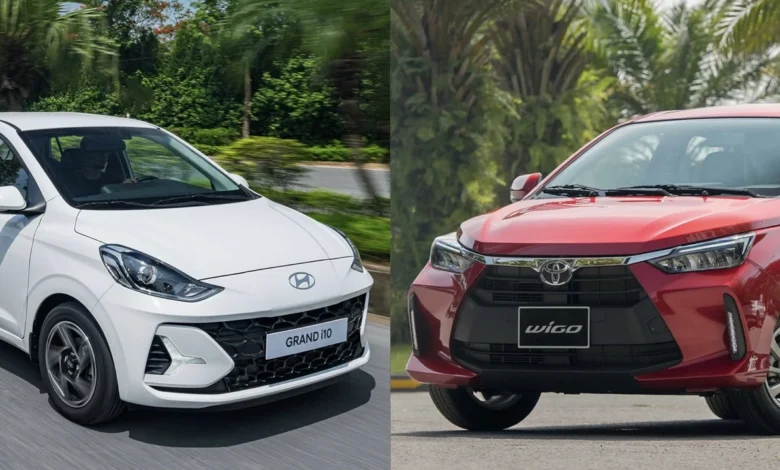
The Vietnamese automotive market has experienced a significant downturn in the A-segment city car category during the month of August, with key players such as the Hyundai Grand i10 and Toyota Wigo recording steep drops in sales volume. Industry reports released in mid-September 2026 indicate that consumer demand for entry-level hatchbacks has cooled noticeably, reversing the temporary momentum observed just a month prior. For the Hyundai Grand i10, the month of August marked a concerning milestone as its sales volume plummeted into the double digits for the first time this year—a stark contrast to its historical performance as a dominant staple in Vietnam’s urban commuter market. Meanwhile, the Toyota Wigo stumbled significantly, losing the retail footing and market enthusiasm it had successfully captured following a surprise surge in July.
This unexpected contraction within the A-segment has prompted automotive analysts, dealership networks, and industry observers to reevaluate the shifting preferences of Vietnamese car buyers. Once viewed as the quintessential entry point for first-time vehicle owners, ride-hailing drivers, and budget-conscious families, the micro-car and subcompact hatchback segments face intensifying pressure from multiple directions. As macroeconomic factors, evolving consumer expectations, and the rapid expansion of more versatile B-segment sedans and entry-level crossovers reshape the domestic automotive landscape, the traditional city car is fighting to maintain its relevance on local roads.
Chronology of the A-Segment Slump: From July Surges to August Corrections
The trajectory of the A-segment market throughout the third quarter of 2026 has been characterized by sharp volatility rather than steady growth. Entering the summer months, automobile manufacturers and local dealerships deployed aggressive promotional campaigns, zero-interest financing structures, and localized registration fee discounts to stimulate consumer spending during a historically sluggish retail period.
In July, these concerted marketing efforts appeared to pay off temporarily. The Toyota Wigo, in particular, delivered a surprising performance that outpaced market expectations, capturing a wave of short-term demand from urban buyers looking for fuel-efficient, compact mobility solutions. Industry trackers noted a notable uptick in showroom traffic, with prospective buyers finalizing purchases ahead of late-summer financial adjustments. The Hyundai Grand i10 also maintained a relatively stable baseline, benefiting from its well-established footprint in commercial fleets and traditional taxi services across major metropolitan hubs like Hanoi and Ho Chi Minh City.
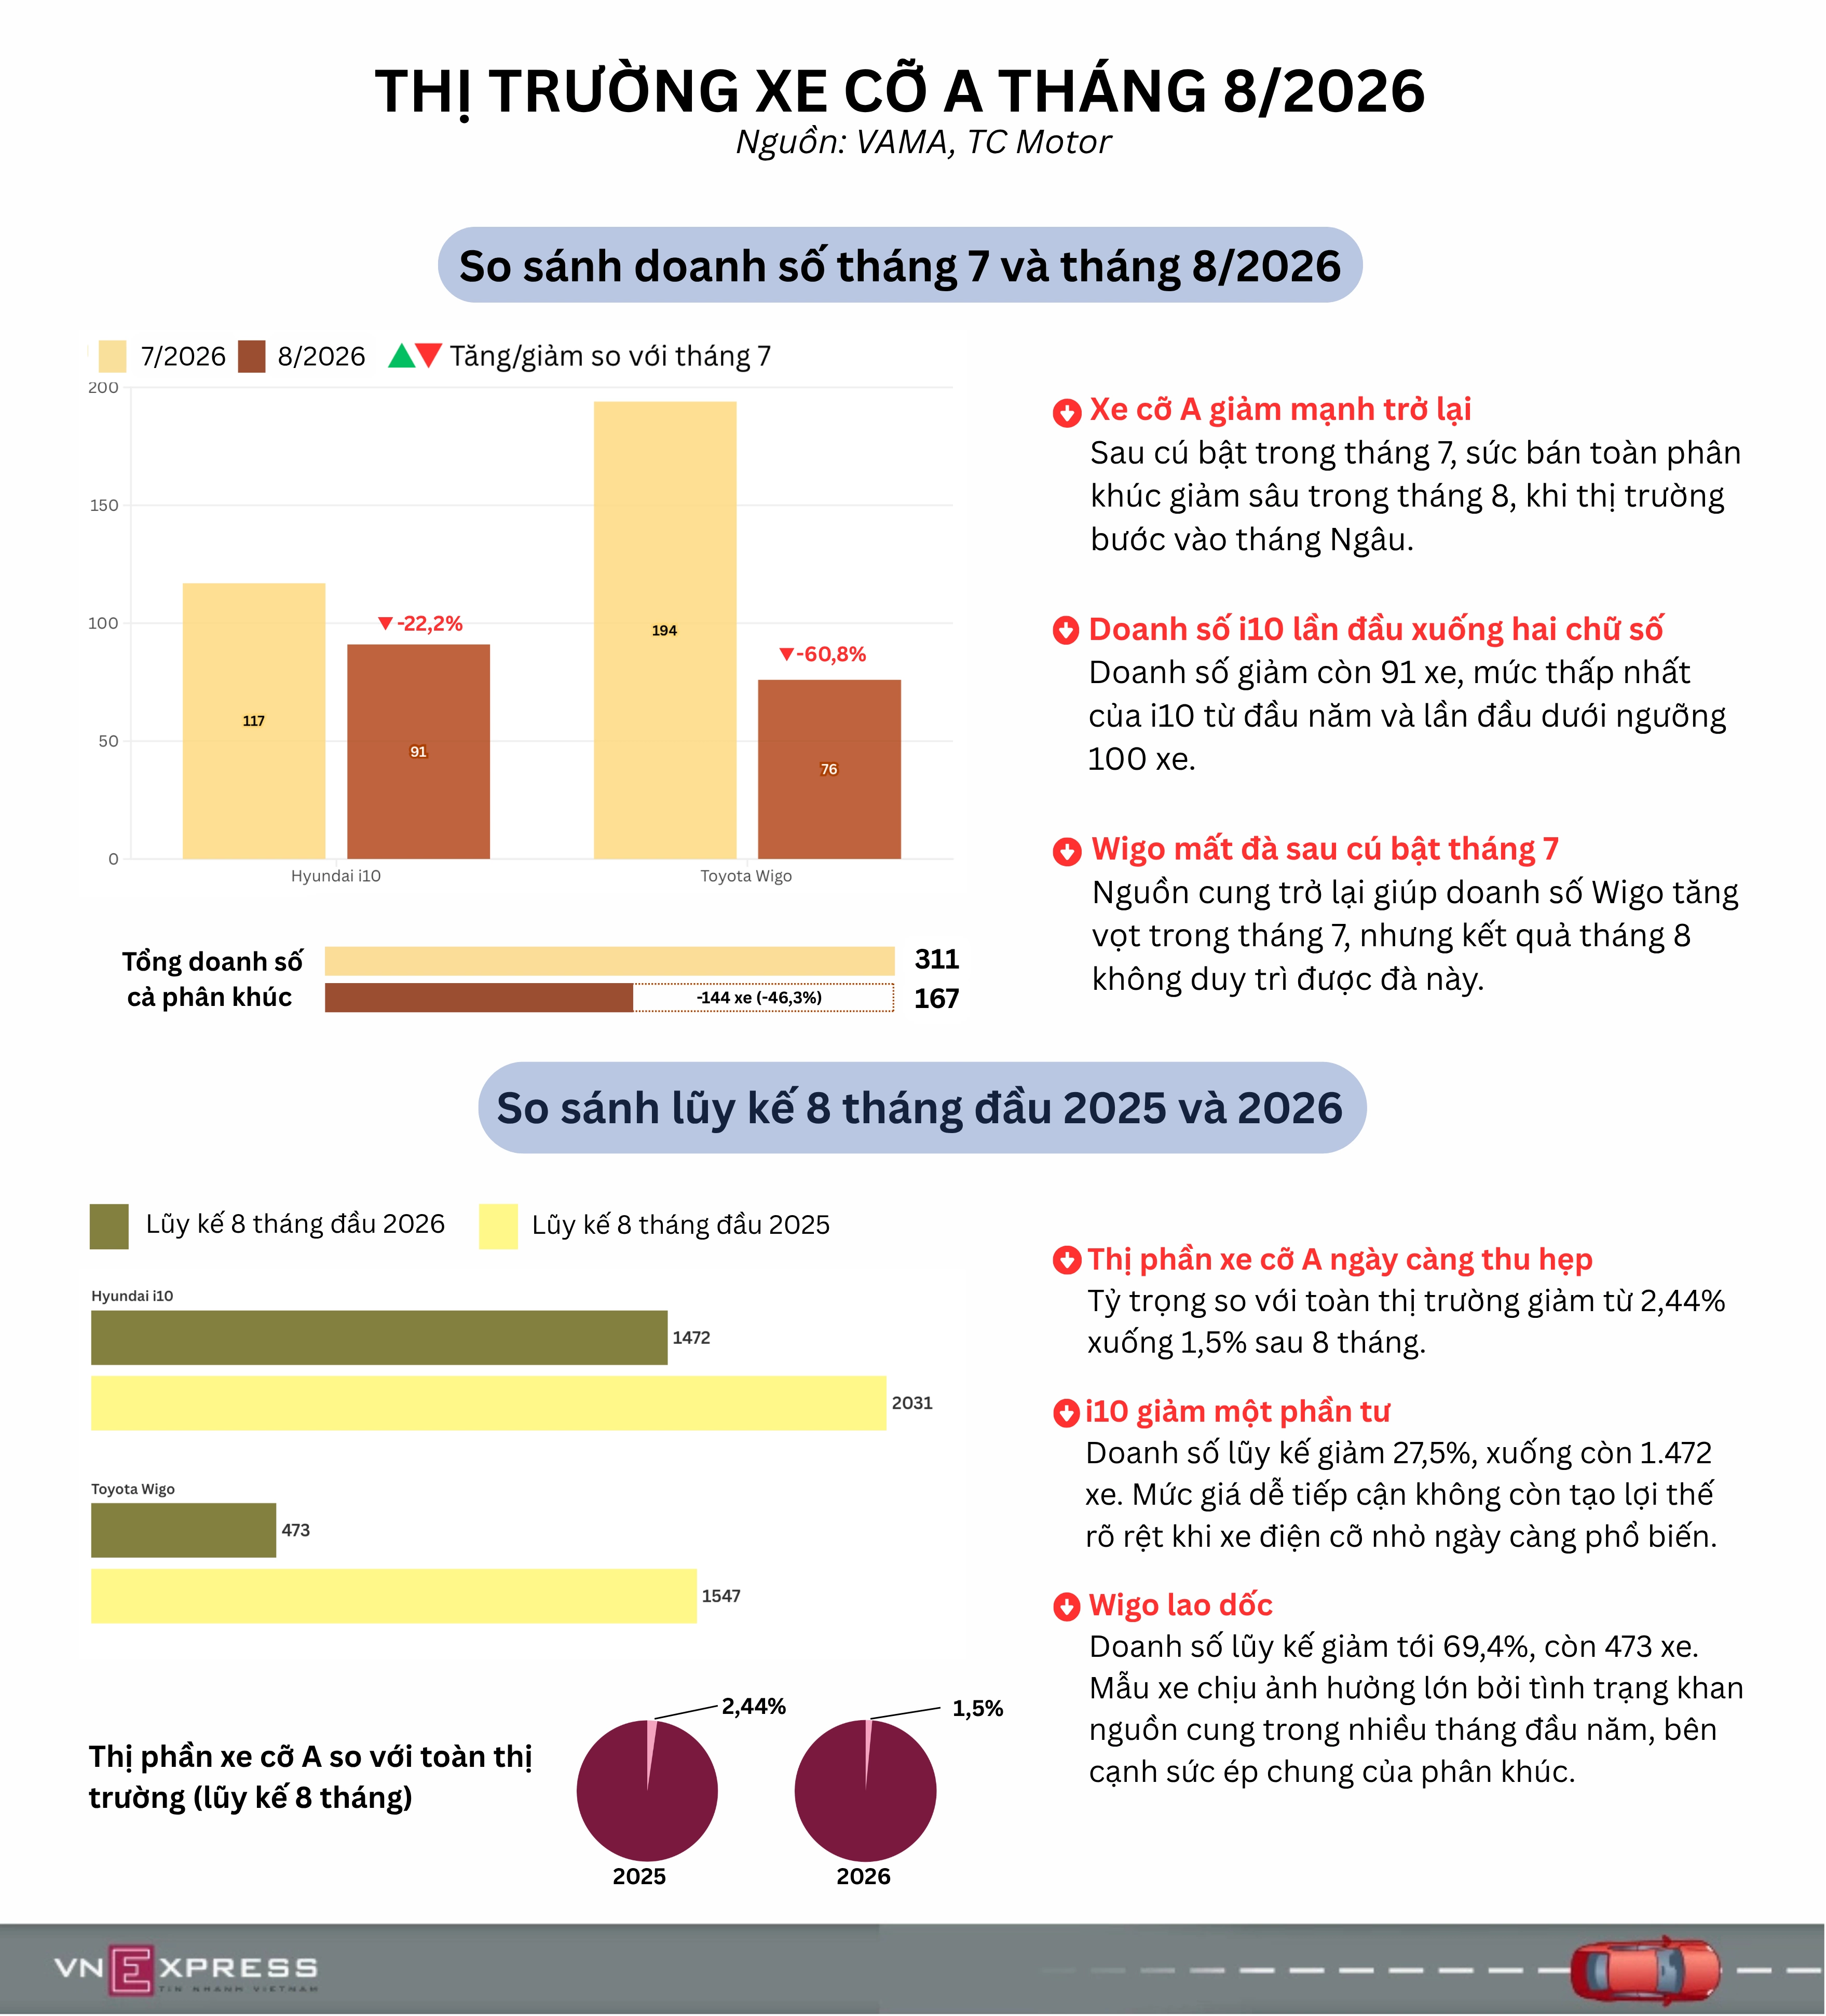
However, the momentum proved short-lived. By August, the market dynamic shifted dramatically. A combination of seasonal factors—including the traditional ghost month (the seventh lunar month), during which many Vietnamese consumers traditionally avoid making major financial investments such as purchasing vehicles—and tightening liquidity across the broader economy severely suppressed showroom activity. As foot traffic dwindled, dealerships reported canceled appointments and delayed purchase decisions. By the time monthly sales ledgers were closed for August, the consequences were severe: the Hyundai Grand i10 suffered a historic drop into double-digit monthly deliveries, while the Toyota Wigo surrendered virtually all the market share gains it had fought for just weeks earlier.
Comparative Market Data and Segment Performance Analysis
A closer examination of the sales figures underscores the vulnerability of the A-segment in the face of broader market currents. Historically, cars priced under 500 million VND ($20,000 USD) served as the volume drivers for mass-market brands in Vietnam. However, shrinking price deltas between A-segment hatchbacks and larger, more feature-rich B-segment sedans have increasingly skewed consumer purchasing behavior.
During August, total deliveries for the Hyundai Grand i10 fell precipitously, breaking a psychological threshold by dropping below the one-thousand-unit mark into double-digit monthly figures—an unprecedented low for a vehicle that has long commanded leadership in its class. Competitors fared no better. The Toyota Wigo, which had celebrated a robust July driven by fleet upgrades and youthful first-time buyers attracted to its modern styling and improved safety features, experienced an equally sharp correction. Sales volumes for the Wigo plummeted by more than half compared to the previous month, neutralizing the optimism generated by its mid-summer rally.
Other niche players in the micro-car category also felt the chill. While localized electric vehicle initiatives and alternative urban mobility options continue to capture public imagination, traditional internal combustion engine (ICE) city cars remain heavily reliant on traditional financing channels and cash buyers. As bank interest rates fluctuated and lenders applied more stringent credit approval criteria for consumer loans, budget-conscious buyers—the core demographic for both the i10 and the Wigo—chose to defer major purchases. Consequently, dealerships found themselves burdened with excess inventory, forcing management teams to contemplate deeper inventory-clearing discounts heading into the final quarter of the year.
Official Responses and Dealership Perspectives
In the wake of the August sales report, representatives from major automotive distribution networks and authorized dealerships have offered candid assessments regarding the state of the entry-level market. Speaking on condition of anonymity, regional sales managers for both Hyundai and Toyota franchise networks acknowledged that consumer psychology has evolved beyond pure affordability.
"The modern Vietnamese car buyer is increasingly pragmatic and value-conscious in a holistic sense," noted one senior dealership executive based in southern Vietnam. "Ten years ago, a customer looking for an A-segment hatchback prioritized the lowest possible purchase price and basic fuel economy. Today, buyers examine total cost of ownership, resale value, advanced safety features, and cabin versatility. When a consumer realizes they can stretch their budget slightly to acquire a B-segment sedan with more legroom, a larger trunk, and superior highway stability, many decide to upgrade rather than settle for a city car."
Furthermore, representatives from manufacturing and assembly plants pointed out that production adjustments are already underway to align output with shifting demand. While the Hyundai Grand i10 continues to anchor commercial and ride-hailing fleet contracts, the reliance on private retail buyers has weakened. Fleet operators, facing their own economic pressures and tighter profit margins in the urban transport sector, have likewise slowed their fleet expansion plans, compounding the delivery slump observed in August.
Toyota franchise dealers echoed similar sentiments, emphasizing that while the Wigo’s design updates and enhanced standard equipment successfully attracted curious buyers in July, sustaining that momentum requires continuous financial incentives that eat into dealer margins. Without aggressive factory-backed subsidies or subsidized loan packages, converting showroom interest into signed contracts has become exceedingly difficult in the current macroeconomic climate.
Broader Economic Implications and Industry Outlook
The sharp contraction of Hyundai i10 and Toyota Wigo sales in August serves as a bellwether for broader shifts within the Vietnamese automotive ecosystem. As Vietnam transitions through a period of economic normalization, consumer spending habits are undergoing structural recalibration.
One major implication of the A-segment slowdown is the acceleration of market stratification. The middle tier of the automotive market is polarizing: buyers with tighter budgets are either delaying purchases or turning to the expanding used car market, while those with slightly greater financial flexibility are skipping A-segment hatchbacks entirely in favor of B-sedans (such as the Toyota Vios or Hyundai Accent) or entry-level high-riding crossovers (such as the Kia Sonet or Toyota Raize). The raised driving position, higher ground clearance, and perceived prestige of compact SUVs have made them formidable alternatives to traditional low-slung city hatchbacks, even within urban environments prone to seasonal flooding.
For manufacturers, the challenge moving forward lies in re-engineering the value proposition of the city car. To reverse the downward trend witnessed in late summer 2026, brands may need to introduce more comprehensive technology packages, improve active safety suites as standard equipment, and introduce innovative leasing or subscription-based ownership models tailored to younger urbanites who prioritize flexibility over traditional asset ownership.
As the industry looks ahead to the final quarter of 2026—historically a peak purchasing season leading up to the Lunar New Year festivities—all eyes will be on whether Hyundai, Toyota, and other mass-market contenders can implement effective recovery strategies. Whether the August slump proves to be an isolated seasonal aberration or the beginning of a permanent structural decline for the traditional A-segment hatchback will depend heavily on upcoming promotional offensives, macroeconomic stabilization, and the adaptability of automakers in meeting the changing demands of Vietnamese motorists.