State Capital Investment Corporation Puts Entire 63.38 Percent Stake in Seaprodex Up for Auction at Over 8.5 Trillion VND

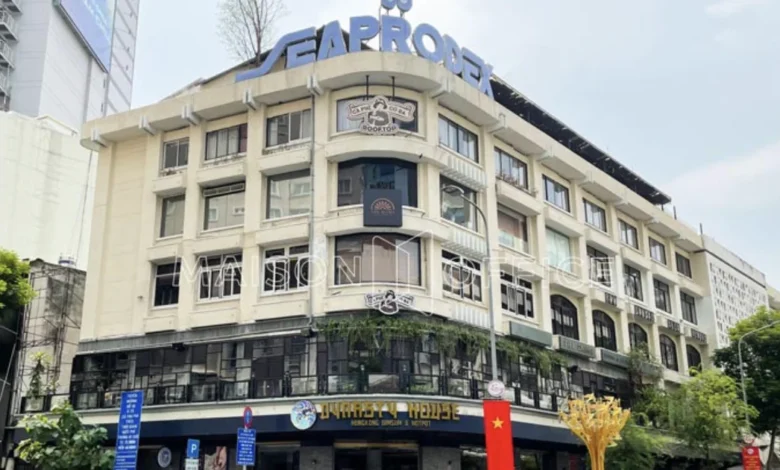
The State Capital Investment Corporation (SCIC) has officially announced plans to divest its entire ownership stake in the Vietnam National Seaprodex Corporation (Seaprodex), setting a minimum auction price of more than 8.509 trillion VND. This major divestment involves a block of 79,228,342 shares, representing 63.38% of the total charter capital of the agricultural and seafood processing enterprise.
The upcoming auction, scheduled to take place at the Hanoi Stock Exchange (HNX) on September 29, 2026, has drawn significant attention from institutional investors, corporate conglomerates, and real estate developers alike. Beyond its historical roots in the fisheries and seafood sector, Seaprodex has increasingly become the focus of market speculation due to its vast portfolio of prime, highly coveted real estate assets situated across major urban centers in Vietnam, most notably in Ho Chi Minh City.
As state-owned enterprises continue to streamline their portfolios and transfer non-core capital back to the state budget, the sale of Seaprodex stands out as one of the most substantial equitization and divestment events of the year. Market watchers and industry analysts are closely monitoring the bidding parameters, valuation metrics, and potential buyer syndicates that may emerge to acquire a controlling stake in an enterprise that holds such irreplaceable urban land reserves.
Auction Parameters and Procedural Timeline
According to the official divestment prospectus released by SCIC, the 79,228,342 shares will not be sold in smaller retail blocks; rather, they are being offered as a single, indivisible lot. The starting price for the entire block has been anchored at 8.509 trillion VND, which mathematically translates to a baseline valuation of approximately 107,400 VND per share.
This pricing strategy reflects a considerable premium over standard historical trading multiples, underscoring the intrinsic value of the underlying assets rather than just the company’s baseline operational earnings from seafood processing. Investors wishing to participate in the open competitive auction must complete their registration processes and deposit the required earnest money by 3:30 PM on September 22, 2026. The auction itself is slated to commence at 9:00 AM on September 29, 2026, at the facilities of the Hanoi Stock Exchange.
The ownership structure of Seaprodex currently features a high concentration of institutional capital. Prior to this divestment announcement, SCIC was the majority shareholder holding 63.38%. The remaining significant shareholders include Ngân Hiệp Joint Stock Company, which maintains a substantial 24.03% stake, and Redwood Investment Joint Stock Company, holding 8.44%. Combined, these three major entities control a staggering 95.85% of the total equity in Seaprodex. Minority public shareholders hold the remaining 4.15% of voting shares, meaning that the acquisition of SCIC’s block effectively transfers absolute managerial and strategic control of the corporation to the winning investor or consortium.
The Crown Jewel: The Prime Property at 2-4-6 Dong Khoi Street
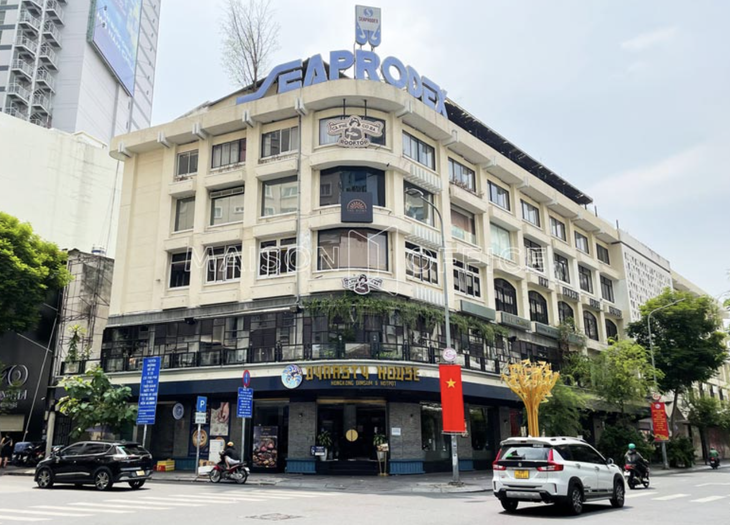
The primary catalyst for investor interest in the Seaprodex auction is the company’s extensive holding of prime real estate, headed by the legendary property located at 2-4-6 Dong Khoi Street in Ben Nghe Ward, District 1, Ho Chi Minh City. Situated in the absolute financial and cultural epicenter of Vietnam’s southern metropolis, this address serves as the official headquarters of Seaprodex.
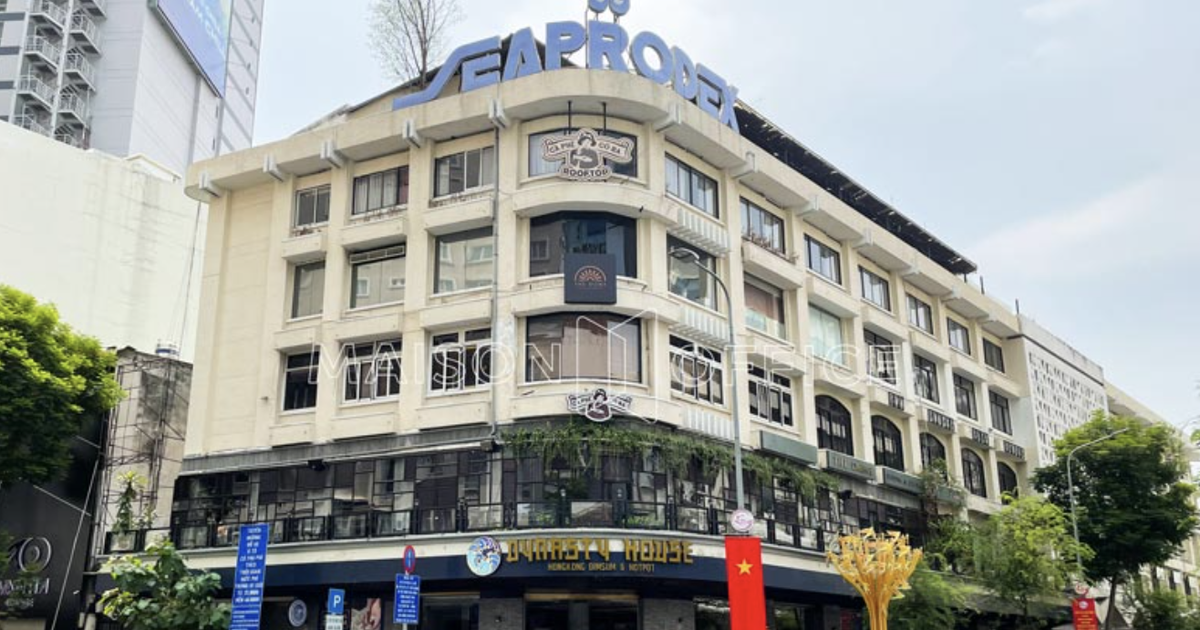
The land parcel is bounded by some of the most prominent thoroughfares in the city center, including Ton Duc Thang Street, Dong Khoi Street, and Ngo Duc Ke Street. In urban planning documents and corporate disclosure statements, this location is frequently described as "golden land" due to its proximity to the Saigon River waterfront, major luxury hotels, high-end retail malls, and commercial financial hubs.
Financial disclosures from Seaprodex indicate that as of June 30, 2026, the corporation recorded nearly 692.7 billion VND in construction-in-progress costs, with the overwhelming majority—approximately 692.17 billion VND—tied directly to the development project at the Dong Khoi address.
Historical Context and Long-Standing Legal Bottlenecks
Despite its astronomical valuation and prime geographic positioning, the development project at 2-4-6 Dong Khoi Street has faced prolonged administrative delays, highlighting the complex regulatory environment surrounding state-associated real estate assets in Vietnam.
According to historical notes in corporate financial reports, the People’s Committee of Ho Chi Minh City approved the land pricing scheme based on market rates for this specific property way back in December 2015. Following this approval, Seaprodex fulfilled its financial obligations, depositing the required land use fees. The District 1 Tax Department officially acknowledged the payment on January 24, 2017, and the Ho Chi Minh City Department of Finance confirmed that the enterprise had fully completed its financial obligations regarding the land on January 27, 2017.
However, despite having paid the required financial dues nearly a decade prior, Seaprodex disclosed in its periodic corporate disclosures in August 2026 that it has yet to be issued the official Certificate of Land Use Rights (frequently referred to as the "red book") by competent state management authorities. Consequently, the commercial development project on the site remains stalled, awaiting final administrative clearance before construction or asset monetization can legally proceed. This lingering legal hurdle represents both a risk and an opportunity for prospective buyers, who must factor potential regulatory navigation costs into their bidding strategies.
Broad Real Estate Portfolio Across Ho Chi Minh City
While the Dong Khoi property commands the highest market value and media attention, Seaprodex’s asset portfolio extends far beyond a single address. Public disclosure documents reveal that the corporation and its various member units manage and utilize an extensive network of land parcels and office buildings in Ho Chi Minh City and several other provinces, each with distinct legal origins, usage terms, and remaining lease durations.
Within Ho Chi Minh City alone, Seaprodex’s portfolio includes:
- An office building at 22-24-26 Mac Thi Buoi Street in Ben Nghe Ward, covering a floor area of 277.8 square meters.
- A residential and commercial land property at 211 Nguyen Thai Hoc Street in Pham Nlao Ward (Ben Thanh Ward area), spanning 243.4 square meters.
- A multi-purpose facility at 97/6 Kinh Duong Vuong Street in Phu Lam Ward, spanning 541.9 square meters.
- A sizable property plot located at No. 7 Nhat Trang Long Street in Gia Dinh Ward, covering 1,187.5 square meters.
In addition to these direct properties, corporate disclosures itemize numerous other smaller land lots, warehouses, and commercial spaces held by Seaprodex subsidiaries and joint ventures across southern and central Vietnam. The diverse legal statuses of these properties—ranging from long-term leased state land to allocated corporate assets—require rigorous due diligence from any institutional investor aiming to consolidate and restructure the corporation’s asset base post-acquisition.
Financial Standing and Operational Performance
To contextualize the massive starting auction price, financial analysts routinely evaluate Seaprodex’s balance sheet alongside its baseline operating performance. As of June 30, 2026, the consolidated total assets of Seaprodex stood at nearly 2.910 trillion VND, while total equity hovered around 2.661 trillion VND.
When evaluating the state’s divestment package through a market lens, the baseline auction price of 107,400 VND per share implies a total implied market capitalization of roughly 13.425 trillion VND for the entire company across its 125 million circulating shares. This valuation figure is roughly 4.6 times higher than the company’s book-value total assets of 2.910 trillion VND. Such a high price-to-book ratio clearly signals that public equity markets and state valuation agencies are pricing Seaprodex primarily as a premier real estate holding entity rather than a traditional seafood processing and export enterprise.
On the operational front, Seaprodex has demonstrated steady, albeit modest, business performance. During the first half of 2026, the corporation reported net revenue of approximately 435 billion VND, marking a 29% increase compared to the same period in the previous year. Net profit after tax reached roughly 105 billion VND, representing a slight contraction from the 107 billion VND recorded during the corresponding period in 2025. Core operations in fisheries, trade, and cold storage continue to generate stable cash flows, yet they constitute only a fraction of the total valuation being commanded by the state’s capital divestment block.
Market Implications and Future Outlook
The upcoming auction of SCIC’s stake in Seaprodex marks a pivotal milestone in Vietnam’s ongoing efforts to divest state capital from enterprises where public ownership is no longer deemed necessary for strategic economic control. By bundling the shares into a single controlling block, the state aims to attract deep-pocketed investors capable of deploying substantial capital to resolve lingering legal bottlenecks, complete long-delayed urban development projects, and unlock the true economic potential of underutilized urban land banks.
For the real estate and financial sectors, the auction will serve as a bellwether for investor appetite regarding large-scale asset privatization in prime urban locations. Given the complexity of the legal status surrounding the Dong Khoi property and the sheer scale of the financial commitment required—exceeding 8.5 trillion VND just to enter the competitive bidding arena—participation is likely to be restricted to major domestic consortiums or strategic partnerships uniting financial institutions with seasoned real estate developers.
As the registration deadline approaches on September 22, 2026, industry stakeholders will monitor whether strategic investors step forward to meet the state’s valuation expectations. The outcome of the September 29 auction at the Hanoi Stock Exchange will not only determine the future ownership of Seaprodex but will also establish a major benchmark for corporate restructuring, state divestment efficiency, and urban asset monetization in Vietnam’s rapidly evolving economic landscape.