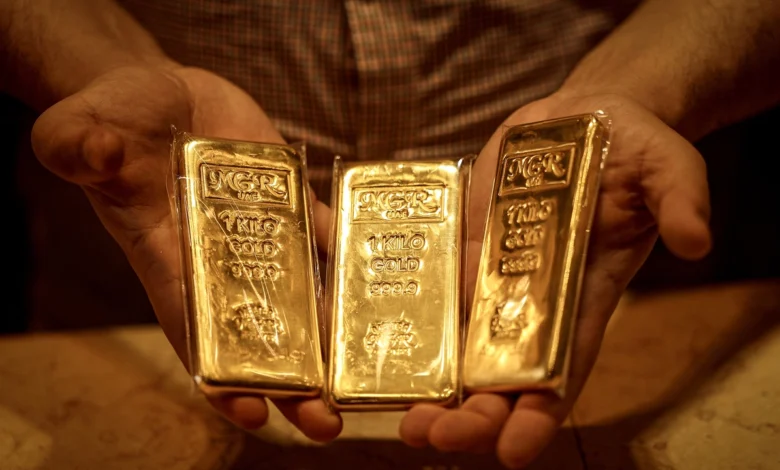
The global gold market is currently undergoing a period of intense scrutiny as major financial institutions and analysts recalibrate their expectations for the precious metal heading into the final quarter of the year. Following a volatile trajectory that saw historic peaks and subsequent sharp corrections, market sentiment is shifting toward a cautious optimism, with industry heavyweights like Goldman Sachs and UOB projecting a potential rally toward the $4,900 to $5,400 per ounce range by late 2024 and through 2027.
A Chronology of Volatility: From Record Highs to Stabilization
The year 2024 has been defined by unprecedented price swings for gold. In January, the market witnessed a monumental milestone when prices surged past the $5,500 per ounce threshold, driven by a confluence of geopolitical tensions and speculative demand. However, the momentum faced a significant reversal by the end of June, as prices plummeted below the $4,000 level.
The turbulence did not end there. By the end of August, gold experienced another sharp recovery, climbing above $4,600 following an announcement by U.S. Treasury Secretary Scott Bessent regarding an expanded program to repurchase Treasury bonds. This rally, however, was short-lived as prices underwent a correction back below the $4,400 mark in early September, pressured by rising U.S. Treasury yields. As of September 11, spot gold was trading near the $4,350 per ounce level. In local markets, the divergence between global prices and domestic gold bars and rings has remained a point of concern, with premiums hovering around 7 million VND per tael.
Institutional Forecasts and the "Bottoming" Theory
Financial analysts are increasingly pointing to signs of a structural floor for gold prices. The Research division at UOB (Singapore) posits that the precious metal has likely established a temporary bottom in the vicinity of $4,000 per ounce. UOB’s multi-year outlook is notably bullish, projecting gold to reach $4,500 in the fourth quarter of 2024, followed by a steady climb to $4,800 in Q1 2027, $5,100 in Q2 2027, and $5,400 by Q3 2027.
Goldman Sachs Research shares this optimistic outlook, maintaining a year-end target of $4,900 per ounce. The primary engine behind this projection remains the persistent and aggressive accumulation of gold reserves by central banks globally. According to current data, net purchases have averaged approximately 50 tons per month throughout 2024—a significant increase compared to the 17-ton average observed in the period leading up to 2022.
Central Bank Accumulation: A Strategic Shift
The structural shift in gold demand is largely attributed to central banks seeking to diversify their foreign exchange reserves. This move is not merely a hedge against inflation but a calculated maneuver to mitigate geopolitical and financial risks. In an era of heightened sanctions and economic fragmentation, gold is increasingly viewed as an asset class that is largely immune to the risk of being frozen or seized, unlike foreign-denominated reserves held in traditional banking systems.
The World Gold Council (WGC) has reinforced this assessment, noting that the combination of central bank buying and long-term institutional investment is creating a new, elevated floor for the market. WGC data suggests that when central bank and institutional investment demand accounts for more than 30% of total global consumption, the impact on price discovery is profound. Estimates indicate that every additional 20–30 tons of gold purchased by central banks can trigger a 1% increase in the price of gold, assuming other market variables remain constant.
Factors Constraining Growth: The Interest Rate Dilemma
While the long-term trajectory appears positive, institutional experts warn of significant headwinds that could dampen growth in the short term. The most prominent risk factor remains the interest rate policy of the U.S. Federal Reserve. Higher interest rates typically exert downward pressure on gold, as they increase the opportunity cost of holding non-yielding assets like bullion, favoring interest-bearing alternatives such as Treasury bonds.
Goldman Sachs notes that while a portion of the investor base began to recover when the market priced in the potential for Fed rate cuts, the persistence of elevated rates continues to be a hurdle. The firm’s research group anticipates that as inflation trends downward, the Fed may maintain a "higher for longer" posture, which could limit significant upside potential for gold through the remainder of 2026.
The World Gold Council’s July report offered a more conservative short-term outlook, suggesting that if current macroeconomic conditions do not change significantly, gold is likely to oscillate within a narrow band, hovering around $4,100 per ounce for the second half of the year.
Potential Catalysts for a Breakout
Despite the potential for stagnation, market experts identify three specific catalysts that could trigger a breakout:
- Macroeconomic Deterioration: A significant weakening in global economic data could reignite safe-haven demand.
- Geopolitical Escalation: Continued conflict, particularly in regions like the Middle East, continues to drive central banks to prioritize physical gold over other reserve assets.
- Monetary Policy Pivot: A clear, definitive signal from the Federal Reserve regarding an aggressive reversal in interest rate policy would likely serve as the primary spark for a move toward the $5,000 level.
Market Dynamics and Derivatives Risks
A secondary, yet critical, element of the current market structure is the role of derivatives and hedging. Goldman Sachs has highlighted that the options trading market could introduce greater volatility in both directions. As participants hedge their positions using complex financial instruments, the resulting "gamma" effects can amplify price swings.
It is worth noting that current price targets, such as the $4,900 year-end projection, often do not fully account for the secondary effects of derivative hedging. While these instruments provide a mechanism for managing risk, they also ensure that gold prices remain highly sensitive to institutional positioning.
Broader Economic Implications
For global investors, the current gold market represents a complex intersection of traditional store-of-value demand and modern geopolitical strategy. The transition from gold being a secondary hedge to a primary component of sovereign reserve management marks a paradigm shift in the international monetary system.
As the year draws to a close, the market will remain hyper-focused on U.S. inflation data, Federal Reserve commentary, and the transparency of central bank buying programs. While the consensus suggests a "bottoming out" process, the path to $5,000 per ounce remains contingent upon a delicate balance between the persistent desire for diversification and the constraints imposed by a global interest rate environment that has yet to fully loosen.
Ultimately, gold’s performance in the coming months will serve as a bellwether for global investor confidence in the traditional financial order. As long as central banks continue to prioritize asset security over yield, the underlying floor for gold appears robust, even if the road to new record highs remains paved with volatility and reactive trading.