A protracted legal battle over a gold loan that originated in early 2012 has finally concluded in Bac Ninh Province, shedding light on the complexities of private lending and the challenges of judicial enforcement in Vietnam. The case, which spans over a decade, highlights the risks associated with informal credit agreements and the difficulties courts face when reconciling long-term debts with fluctuating market values and interest rate regulations.
The Origins of the Debt
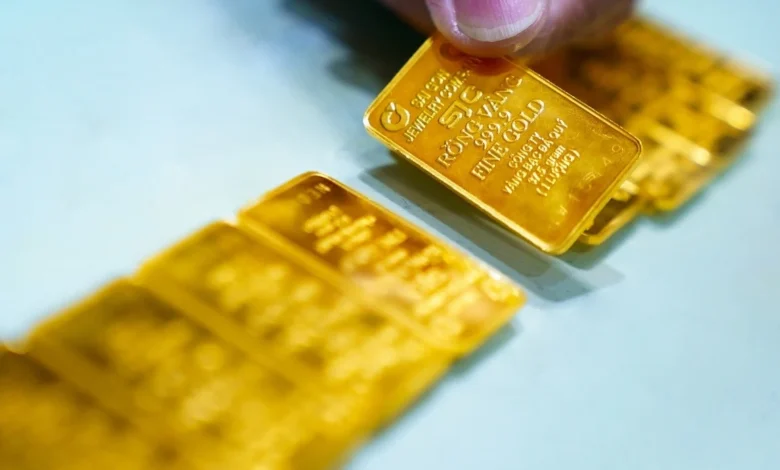
On January 20, 2012, a private loan agreement was formalized at the residence of Mr. Pham Van C. and his wife, Mrs. Pham Thi M., in Bac Ninh. The couple entered into a contract to lend 3.2 taels of SJC-branded gold to Mr. Duong Ngoc T. and his wife, Mrs. Nguyen Thi T. At the time, the agreement was straightforward: the borrowers received the gold, with a stipulated interest rate of one million VND per tael per month. The contract, hand-written and signed by both parties, mandated the repayment of both the principal amount and the accrued interest.
However, the financial stability of the borrowers proved fragile. Within three to four months of receiving the loan, the T. family’s business operations began to face significant economic headwinds. The initial intent to utilize the gold as a capital injection for business growth turned into a struggle for survival. As the family’s financial situation deteriorated, the repayment of the loan became impossible. Despite repeated requests from Mr. C. and Mrs. M. for the return of the gold, the debt remained unpaid, leading to a long-term impasse that eventually escalated into a formal lawsuit.
Chronology of the Legal Proceedings
The timeline of this dispute underscores the longevity of the conflict:
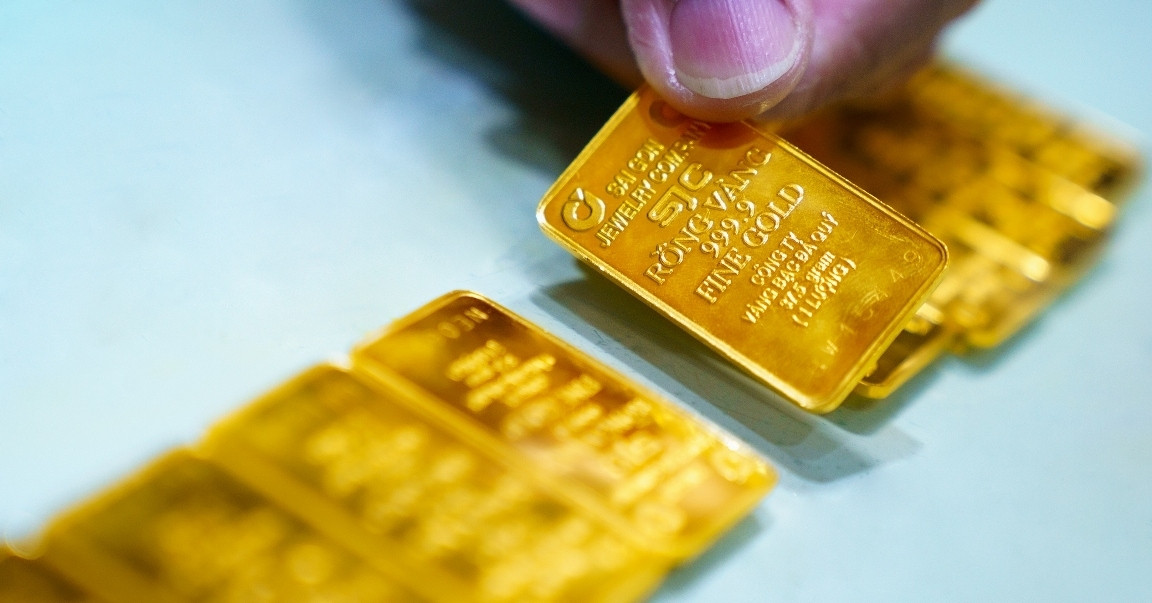
- January 20, 2012: Loan agreement signed for 3.2 taels of SJC gold.
- Mid-2012: The borrowers experience financial distress; default on the loan begins.
- 2019: Mrs. T. reports making partial repayments totaling 67 million VND, though this remains a point of contention due to a lack of formal, undisputed documentation.
- 2023: After completing other legal obligations at the local level, the T. family is again approached by the lenders, but they remain unable to settle the debt.
- March 30, 2026: The People’s Court of Bac Ninh Province holds a first-instance trial.
- April 3, 2026: The lenders appeal the initial ruling, challenging the court’s decision regarding interest and the valuation of the gold.
- July 17, 2026: The appellate court issues its final verdict (Judgment No. 227/2026/DS-PT).
Judicial Rulings and Conflicts over Valuation
The legal process was marked by significant disagreements regarding how to calculate the value of the debt after 14 years. During the first-instance trial, the parties reached a consensus to convert the 3.2 taels of gold into currency at a rate of 150 million VND per tael, totaling 480 million VND. However, the lenders, Mr. C. and Mrs. M., insisted on additional interest payments covering the 166 months between 2012 and 2025. They argued for a total repayment of nearly 1 billion VND, accounting for the interest rate of 3.2 million VND per month.
The court, however, took a different stance. The first-instance panel rejected the claim for 531.2 million VND in interest, arguing that the law at the time of the agreement and during the adjudication did not provide clear provisions for interest rates on gold-denominated loans. This decision reflected a cautious judicial approach, aimed at preventing excessive usury in informal lending sectors.
Upon appeal, the lenders argued that the court should have applied market-linked interest rates or at least a 10% annual interest rate on the value of the gold over the 13-year period. Mrs. T. strongly opposed this, maintaining that she had already paid 67 million VND, despite her inability to produce physical proof of all payments due to the alleged destruction of records by the lenders.
The Appellate Verdict
The appellate court ultimately upheld the first-instance ruling, dismissing the lenders’ appeal for additional interest. The court reaffirmed that since both parties had voluntarily agreed to convert the gold into 480 million VND, that figure was the legally binding debt. Regarding the request for interest, the court stated there was no legal basis for applying retrospective interest calculations for the entire duration of the loan.
The court clarified that the interest for "late payment" would only accrue from the date the judgment took legal effect and the creditors submitted a formal request for enforcement. The court noted that there was no precedent or statutory requirement to retroactively calculate interest for the years between 2012 and the final verdict, effectively capping the total liability at the agreed-upon 480 million VND.
Broader Economic Implications
This case serves as a cautionary tale regarding the risks of "informal lending" (often referred to as the black credit market in Vietnam). While personal loans are a common feature of the Vietnamese economy, the lack of formal banking oversight and clear contractual safeguards often leads to prolonged litigation that serves neither the creditor nor the debtor.
Financial analysts suggest that this case highlights several critical points for the public:
- Documentation is Paramount: The dispute over the 67 million VND payment demonstrates that without clear, signed, and witnessed receipts, oral agreements or informal notes are virtually impossible to enforce in a court of law.
- Asset Volatility: Lending in gold presents a unique challenge in inflationary environments. As the price of gold rises, the gap between the original value and the current market value can lead to intense legal disputes, as evidenced by the lenders’ attempts to adjust their demands based on the soaring price of precious metals.
- Limitations of Judicial Recourse: The courts are strictly bound by the laws as they were written at the time of the contract. In many cases, judicial bodies are hesitant to impose interest rates on informal contracts that do not strictly comply with commercial lending regulations, leaving creditors with lower returns than they might have expected.
The decision by the Bac Ninh appellate court brings an end to a 14-year saga, but it leaves behind a complex legacy. For the lenders, the outcome was significantly lower than their desired financial recovery. For the borrowers, the court-mandated 480 million VND represents a heavy burden after years of financial struggle.
Conclusion
As the Vietnamese legal system continues to refine its approach to civil disputes and private debt, cases like this underscore the necessity for formal, transparent, and legally binding financial agreements. The reliance on informal contracts—while culturally ingrained—remains a significant vulnerability for households and small business owners alike. Moving forward, authorities are likely to continue encouraging the use of regulated financial institutions to avoid the pitfalls of long-term, non-documented debt that often results in social tension and protracted litigation. This case in Bac Ninh will undoubtedly serve as a reference point for future disputes involving long-term private lending, emphasizing the primacy of written, unambiguous contracts in the eyes of the law.