State-owned enterprises face delisting risks as fund management sector struggles with retail investor short-termism and low NAVs

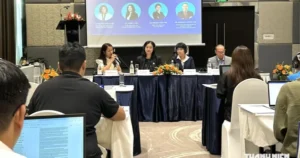
Vietnam’s fund management industry is undergoing a pivotal transformation, transitioning from a nascent market sector into a foundational pillar of the nation’s broader capital market. Despite this trajectory, the industry faces structural hurdles, chief among them being the heavy reliance of retail investors on short-term speculative trading rather than long-term asset accumulation. This dynamic came under the spotlight at the recent high-level industry event titled Industries in a New Era: Unlocking Capital Flows for High and Sustainable Growth, held in late September 2026.
The event convened key regulators, asset managers, and securities industry executives to address the pressing need to redirect Vietnam’s vast pool of retail liquidity away from high-risk, speculative channels—such as short-term equity flipping and physical real estate—and into professionally managed, long-term collective investment vehicles. With Vietnam’s stock market recently upgraded to secondary emerging market status by FTSE Russell, the urgency to restructure the domestic investor base has never been more pronounced. Regulatory authorities and industry leaders alike are racing to build a resilient, institutionalized financial ecosystem capable of absorbing large-scale domestic and international capital.
The Current Landscape: Growth Amid Structural Limitations
By the end of June 2026, Vietnam’s asset management landscape comprised 43 licensed fund management companies overseeing a total of 141 investment funds. Total assets under management (AUM) by these firms—inclusive of discretionary portfolio management mandates—reached approximately VND 846,000 billion, equivalent to roughly $32.5 billion USD. Over the preceding decade, total assets managed by these firms expanded at a compound annual growth rate (CAGR) of nearly 20%. Notably, open-ended funds and Exchange-Traded Funds (ETFs) have emerged as the dominant growth drivers, currently accounting for roughly 80% of total net asset value (NAV) within the collective investment sphere.
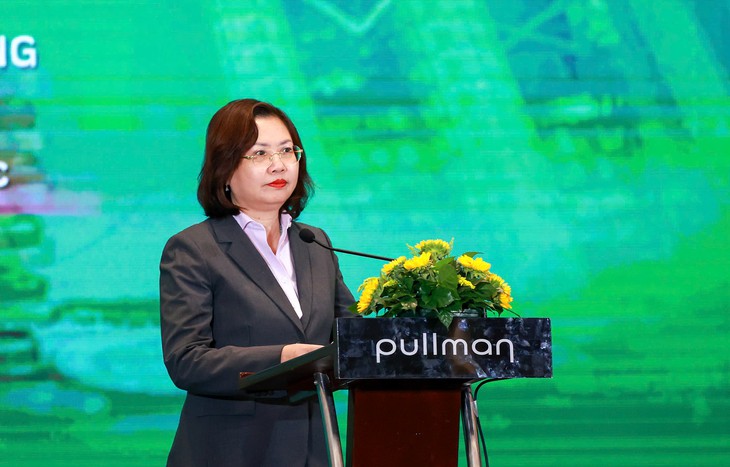
Despite these impressive growth metrics, structural imbalances persist. Speaking at the September forum, Mrs. Vũ Thị Chân Phương, Chairperson of the State Securities Commission (SSC), emphasized that the development of the fund management sector is not merely about launching new investment products for public consumption. Instead, the primary objective is to forge a formidable cohort of professional institutional investors capable of aggregating fragmented societal savings into professionally managed pools of capital. These pools can then be allocated strategically to economic sectors capable of generating long-term, sustainable value.
However, a stark dichotomy remains evident within the market. Even though total AUM managed under discretionary accounts appears substantial, the collective Net Asset Value (NAV) of domestic retail funds remains remarkably constrained, hovering well below the VND 100,000 billion threshold. This discrepancy is particularly striking when juxtaposed against the broader retail participation boom, which has seen the number of individual securities trading accounts approach nearly 14 million. The core paradox facing Vietnam’s financial markets is clear: while millions of individual retail accounts are active on the stock exchange, the vast majority of retail capital bypasses professional collective investment schemes in favor of direct, speculative trading.
Psychological and Behavioral Barriers to Long-Term Investing
Industry leaders attending the September forum pointed to entrenched behavioral patterns and cultural preferences as primary obstacles to the expansion of open-ended and long-term funds. Mrs. Nguyễn Thị Hằng Nga, Deputy General Director of Vietcombank Fund Management (VCBF), noted that the primary challenge facing the growth of open-ended funds is no longer a lack of product diversity. Traditional financial products—such as equity funds, bond funds, balanced funds, and money market funds—are already well-established within the regulatory framework. Instead, the persistent barrier lies in investor awareness, financial literacy, and institutional trust.
Echoing these sentiments, Mrs. Đỗ Thúy Linh, Chairperson of Smart Invest Securities JSC, highlighted insights gathered directly from client advisory operations. According to Mrs. Linh, a major impediment is the psychological categorization of asset classes by retail investors. Despite empirical evidence demonstrating the consistent long-term performance of professionally managed funds, a significant portion of individual investors continue to treat the stock market primarily as a venue for short-term speculation.
Under this prevailing mindset, short-term "idle money" is frequently channeled directly into equities for rapid day-trading and tactical "wave-riding," while longer-term savings intended for capital preservation are funneled into physical real estate—traditionally viewed as a tangible, safe-haven asset. This behavioral bias poses a formidable challenge for financial institutions seeking to cultivate a disciplined, long-term investment culture. Securities firms and fund managers can no longer rely solely on transactional sales of standalone products; they must evolve into holistic wealth management providers capable of tailoring asset allocation strategies to individual financial goals and risk tolerances.
Regulatory Evolution and Institutional Reforms
To address these systemic challenges, the State Securities Commission has outlined an aggressive reform agenda aimed at reshaping the capital market’s foundational architecture. A core priority for the regulatory body in the coming period is the restructuring of the investor base, increasing the proportion of institutional and professional investors relative to retail speculators. The ultimate goal extends beyond merely increasing the number of institutional entities; it involves building a balanced, professional market infrastructure capable of supplying reliable, long-term capital to the broader economy.
Regulatory bodies have taken concrete steps to expand the legal and operational framework for collective investment schemes. A notable milestone in this regulatory evolution is the issuance of Circular 136/2025/TT-BTC, which broadens the legal framework to encompass innovative financial products. This circular introduced provisions for high-yield corporate bond funds, money market mutual funds, and established explicit operational regulations for index-tracking exchange-traded funds. By diversifying the suite of available products, regulators aim to cater more precisely to the evolving risk-return profiles of domestic savers.
Furthermore, regulatory authorities are placing renewed emphasis on investor education and public outreach. The SSC has underscored that future public dissemination campaigns must move beyond generic financial literacy messaging. Instead, educational initiatives must focus on practical, high-impact topics: the structural characteristics and operating mechanisms of various fund types, associated fee structures, liquidity profiles, risk metrics, and principled asset allocation frameworks. By systematically addressing information asymmetries, regulators hope to demystify fund investing and progressively instill a disciplined, long-term investment ethos among Vietnam’s millions of retail market participants.
Broader Implications for Vietnam’s Capital Markets
The strategic push to expand the fund management industry arrives at a critical juncture for Vietnam’s financial system. Following FTSE Russell’s elevation of Vietnam to secondary emerging market status, the nation’s capital markets are bracing for a substantial influx of foreign institutional capital. However, sustainable market development cannot rely solely on foreign inflows; it requires a robust, deep domestic institutional investor base capable of providing market stability and price discovery.
Without a significant transition from short-term retail speculation to professional asset management, the Vietnamese stock market remains vulnerable to sentiment-driven volatility and liquidity crunches. Moreover, companies—particularly state-owned enterprises undergoing equitization and privatization—face ongoing structural risks, including potential delistings or depressed valuations, if domestic institutional demand fails to match corporate capital-raising needs.
As asset managers, securities firms, and regulators collaborate to reform distribution channels and upgrade wealth advisory services, the ultimate success of Vietnam’s capital market hinges on changing the mindset of the domestic investor. By bridging the gap between millions of retail trading accounts and professionally managed funds, Vietnam can successfully channel its vast internal savings toward sustainable economic growth, ensuring that its financial markets mature in tandem with its rapidly expanding national economy.