Actuarial Thinking Becomes Essential Tool for Long-Term Financial Decisions Amid Rising Global Uncertainties

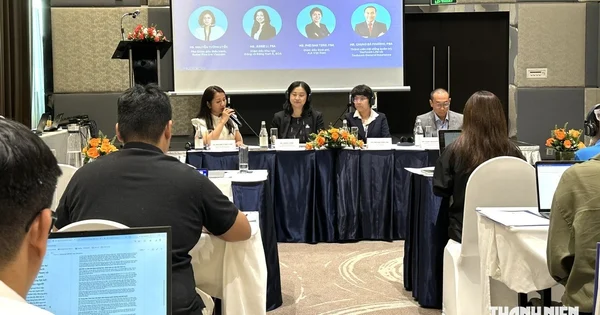
In an era defined by rapid macroeconomic shifts, unpredictable volatility, and escalating systemic complexities, the traditional boundaries of financial decision-making are undergoing a profound transformation. On September 21, 2026, industry leaders, actuaries, and financial strategists gathered in Vietnam for a high-profile symposium titled "Financial Decisions in the Era of Risk Management in Vietnam." Organized by the Society of Actuaries (SOA)—the world’s largest actuarial professional organization—the event served as a critical platform for dissecting how institutions and individuals must adapt their planning models to survive and thrive in an increasingly uncertain world.
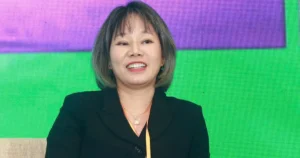
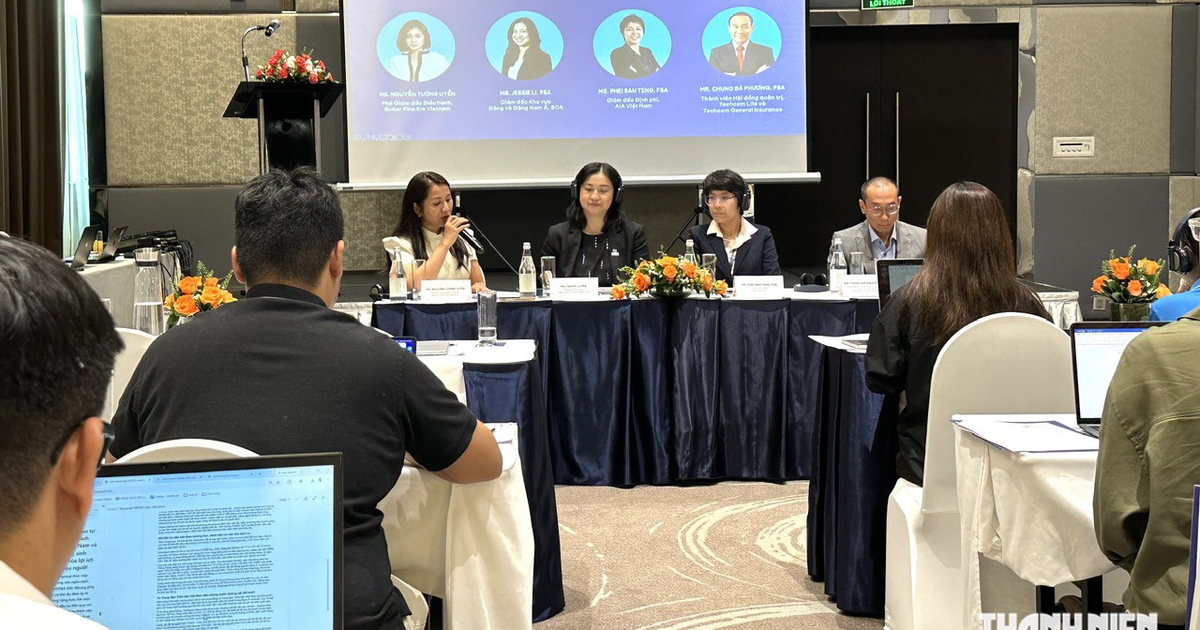
Opening the discourse at the symposium, Ms. Jessie Li, FSA, Regional Director for East and Southeast Asia at the Society of Actuaries, delivered a keynote address that underscored the growing inadequacy of short-term financial models. As emerging risks intersect with unprecedented demographic and technological changes, evaluating the long-term effectiveness of financial decisions has become a formidable challenge. According to Ms. Li, this pivotal moment calls for a complete paradigm shift: actuarial thinking must transcend its traditional niche roles to actively shape the structural framework and long-term vision of complex financial decisions across both corporate boardrooms and individual households.
The Demographic Shift and Vietnam’s Aging Population
To illustrate the vital necessity of integrating actuarial foresight into modern financial planning, Ms. Li pointed to Vietnam’s rapid demographic transition as a prime, real-world case study. Projections indicate that by the year 2036, nearly 20 percent of Vietnam’s population will be aged 60 or older. This structural graying of the population brings forth an intense, multi-layered pressure on future retirement planning, surging healthcare expenditures, and the overall longevity of accumulated financial assets.
This demographic reality highlights a stark disconnect between public financial confidence and actual preparedness. Findings from the SOA’s comprehensive research report, titled "Financial Preparedness for Retirement in Vietnam 2025," reveal a troubling gap in consumer perceptions. While an overwhelming 71 percent of survey participants expressed confidence that their current personal savings would adequately sustain them through their golden years, a much smaller minority—only 39 percent—realistically understood the need to initiate long-term, disciplined accumulation strategies early in life.
Such discrepancies demonstrate that prevailing short-term financial planning models fail to fully reflect the harsh realities of long-term risk. Today’s saving goals can easily be derailed by unforeseen variables, such as extended life expectancies, soaring medical costs driven by inflation, or macroeconomic shocks that systematically erode purchasing power.
Navigating Corporate Risk in the Age of Artificial Intelligence
While individual households face the perils of underestimating longevity and inflation, corporate environments encounter an equally daunting landscape. The rapid proliferation of big data and artificial intelligence (AI) has dramatically enhanced predictive capabilities, yet these technological tools alone cannot replace critical human judgment. Algorithms can process historical data at unprecedented speeds, but they struggle to interpret novel scenarios or formulate strategic decisions amid structural market disruptions.
During panel discussions at the SOA symposium, risk management experts emphasized that contemporary financial managers can no longer afford to rely exclusively on historical data models. Instead, decision-makers must actively construct diverse stress-test scenarios, project corresponding financial impacts, and explicitly identify essential strategic trade-offs. The true challenge lies in seamlessly connecting raw data, systemic volatility, and long-term financial outcomes.
While modern analytical tools and data science provide the scaffolding required to support executive oversight, they must be paired with rigorous actuarial logic. This is precisely why organizations are increasingly demanding actuarial professionals who possess a deep comprehension of the broader business context, the analytical agility to challenge prevailing assumptions, and the communication skills to articulate complex risk exposures to non-technical stakeholders. The ultimate value of modern risk analysis does not reside merely in generated numbers, but in transforming raw data into actionable, resilient solutions that empower executives to navigate turbulent markets with confidence.
The Evolving Mandate of the Society of Actuaries in Southeast Asia
The symposium in Vietnam reflects a broader regional initiative by the Society of Actuaries to elevate risk management standards across emerging economies in East and Southeast Asia. As these economies integrate more deeply into global financial networks, they become increasingly susceptible to external market shocks, climate-related disruptions, and regulatory shifts.
The SOA has continuously expanded its educational footprint and professional outreach in Vietnam, aiming to bridge the talent gap in advanced risk assessment. By equipping local financial institutions, insurance providers, and regulatory bodies with world-class actuarial methodologies, the organization seeks to foster a more robust financial ecosystem capable of withstanding future crises. Experts at the conference noted that as Vietnam transitions toward an upper-middle-income economy, the complexity of its financial products—ranging from multi-layered pension funds to sophisticated health insurance structures—will necessitate a proportional upgrade in actuarial oversight.
Broader Implications and Strategic Recommendations
The insights shared at the September 2026 SOA event carry profound implications for multiple tiers of society, urging a coordinated response from policymakers, corporate leaders, and individual citizens alike.

For policymakers and regulators, the findings underscore the urgency of modernizing national social safety nets. As the dependency ratio shifts with the aging population, regulatory frameworks governing pension funds, insurance solvency, and healthcare financing must become more flexible and forward-looking. Encouraging private-sector participation in long-term savings schemes through tax incentives and transparent regulatory oversight will be critical in mitigating future fiscal strains on the state budget.
For corporate entities—particularly within the banking, investment, and insurance sectors—the mandate is clear: risk management must evolve from a compliance-driven checkbox into a core strategic driver. Chief Risk Officers (CROs) and Chief Financial Officers (CFOs) are urged to embed actuarial scenario-planning into their overarching corporate strategy, ensuring that capital allocation models account for tail risks and long-term structural changes rather than short-term quarterly gains.
For individuals, the core takeaway is the urgent need to recalibrate personal financial literacy. Relying on intuition or generic savings habits is no longer sufficient in an inflationary environment marked by increasing life expectancies. Financial advisors recommend adopting comprehensive, long-term wealth accumulation strategies that factor in potential health crises, career interruptions, and extended retirement horizons.
Ultimately, the dialogue fostered by the Society of Actuaries in Vietnam serves as an important reminder that while the future remains inherently unpredictable, the tools to navigate it are well within reach. By bridging the gap between quantitative data and qualitative strategic judgment, stakeholders across Vietnam can build a more secure, resilient financial future capable of withstanding the trials of the coming decades.