E-commerce Tax Compliance Debate: Should Sellers on Platforms with Automatic Tax Deductions Be Exempt from Issuing Individual Invoices?

The intersection of e-commerce expansion and tax administration has triggered intense debate across Vietnam’s financial and regulatory sectors. In a recent comprehensive report submitted to the National Assembly, the Vietnamese Government outlined its ongoing directives to the Ministry of Finance to study and streamline administrative procedures regarding electronic invoices (e-invoices). The core objective is to significantly reduce compliance costs for businesses and individual household businesses, while modernizing tax collection mechanisms. Among the most discussed proposals is whether sellers operating on e-commerce platforms that automatically deduct taxes per transaction should be exempted from the mandatory issuance of individual invoices for every single sale.
While tax experts and legal advisors generally view the proposal as a progressive step toward reducing administrative burdens, they emphasize the need for a flexible implementation framework. Specifically, experts suggest allowing consolidated monthly e-invoicing for transactions where buyers do not request an individual invoice. This approach aims to harmonize the necessity of transparent tax oversight with the practical realities of high-volume, digital-first retail operations.
Evolution of E-Invoice Regulations in Vietnam’s Digital Economy
To understand the weight of the current debate, it is essential to examine the regulatory trajectory of electronic invoices in Vietnam. Over the past decade, the Ministry of Finance and the General Department of Taxation have aggressively pushed for the digitalization of commercial transactions. The nationwide rollout of e-invoices mandated that all corporate enterprises and qualifying business households utilize digital receipts to track revenue and verify tax obligations.
Initially designed to combat tax evasion, create a level playing field, and eliminate the rampant abuse of paper invoice trading, the e-invoicing system quickly became the backbone of modern tax administration. Under current regulations, e-invoices are compulsory for corporate entities, while household businesses meeting specific revenue thresholds—such as those generating an annual turnover of 1 billion VND or more—are also legally bound to issue them.
However, the exponential growth of e-commerce platforms, social commerce, and digital marketplaces has introduced unprecedented transaction volumes. Millions of micro-transactions occur daily across platforms like Shopee, Lazada, Tiki, and TikTok Shop. Consequently, the volume of data flowing through the General Department of Taxation’s central e-invoice repository has skyrocketed. This massive data influx has imposed substantial operational, maintenance, and storage costs not only on state agencies managing the infrastructure but also on individual sellers and small business households who must maintain dedicated software and archiving systems.
The Mechanics of Platform-Based Tax Deductions and Proposed Relief
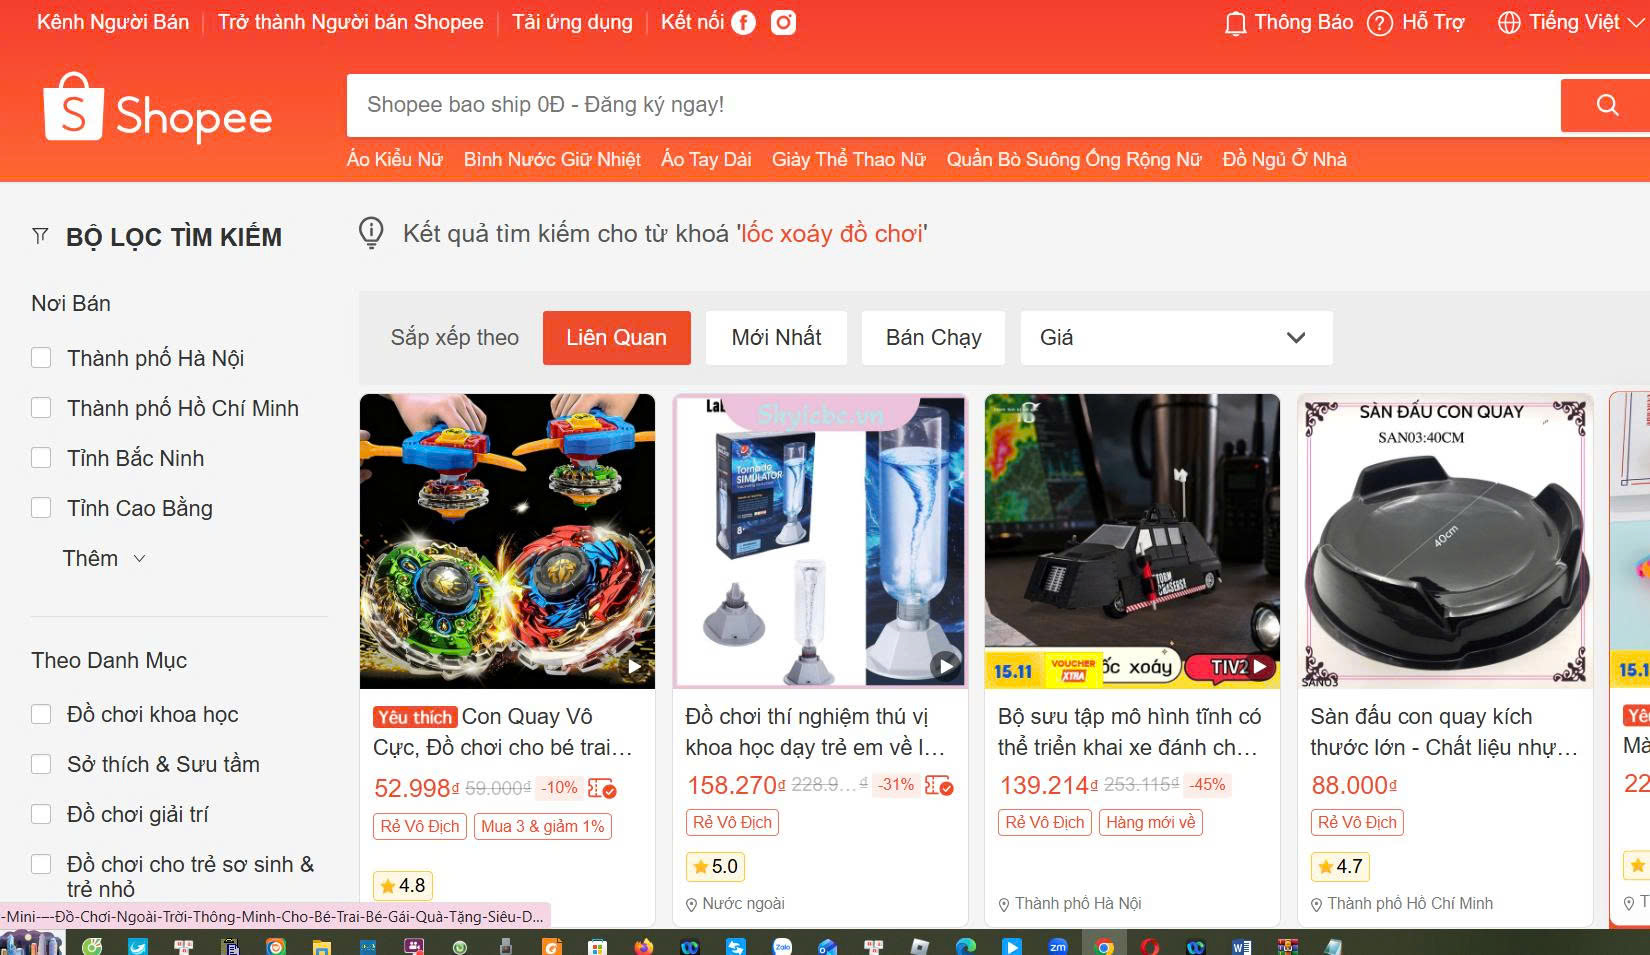
The current friction lies in the redundancy of data processing. Under several modern e-commerce models, marketplaces equipped with integrated payment gateways already perform automated tax deductions and remittances on a per-transaction basis. These platforms maintain comprehensive databases capturing the identities of both buyers and sellers, exact transaction values, timestamps, and verifiable banking records.
Le Van Tuan, Director of Keytas Tax Accounting Co., Ltd., points out that utilizing electronic data as a direct substitute for individual e-invoices is a logical evolution. According to Tuan, an e-invoice is essentially an intermediary data form used to establish tax obligations. If tax authorities can directly harness alternative, highly reliable data sources—such as verified transaction logs from e-commerce platforms and partner banks—the intermediary layers can be safely bypassed.
"When platforms execute tax deductions per transaction, the seller is effectively prevented from engaging in tax evasion or illicit invoice trading in those specific instances," Tuan explains. "Every transaction occurs transparently and is confirmed by empirical financial data. Tax authorities simply need to integrate this verified data source directly into the overarching tax database."
Because these e-commerce platforms exclusively disburse funds to the verified bank accounts of registered sellers and strictly prohibit cash transactions for platform-managed sales, the revenue stream is inherently traceable. This high degree of transparency raises a pertinent question among business communities: If the state already possesses exhaustive, reliable transaction data reported periodically by the e-commerce platform, why must sellers endure the redundant administrative cost of generating millions of individual e-invoices?
Expert Perspectives: Balancing Compliance with Operational Flexibility
While the direction toward administrative simplification is widely welcomed, legal and tax advisory bodies caution that any regulatory shift must carefully balance state oversight with consumer rights and commercial protections.
Lawyer Nguyen Van Hau, Standing Member of the Executive Committee of the Vietnam Tax Consultants Association (VnTCA), emphasizes that while streamlining is necessary, policymakers must account for the dual nature of invoices. In commercial law, an invoice functions simultaneously as a tax obligation fulfillment document for the seller and a legal consumer right for the buyer. Invoices serve as legal proof of ownership, substantiate personal asset records, and act as primary legal foundations for resolving consumer disputes related to counterfeit, substandard, or defective goods.
"If a buyer specifically requests an invoice, the seller must legally comply and provide it," Hau notes. "However, the core challenge arises when the buyer has no demand for an invoice—a scenario that represents the vast majority of retail transactions on e-commerce platforms."
To address this, legal experts and tax consultants have proposed a hybrid mechanism: allowing businesses and household sellers on payment-integrated e-commerce platforms to compile and issue consolidated e-invoices on a periodic basis, such as once a month, corresponding with regular tax reconciliation cycles.
"A monthly reconciliation period is entirely appropriate," Hau elaborates. "Because e-commerce operations are continuously monitored and audited by platform algorithms and banking systems, there is no absolute necessity to aggregate data on a daily basis. Shifting to a monthly consolidated invoicing model would drastically cut compliance time and software maintenance expenses for taxpayers while upholding the foundational legal principle that all commercial sales are ultimately accounted for."
Broader Economic Implications and the Path Forward
The discussion surrounding e-commerce e-invoice exemptions aligns with the broader national agenda spearheaded by the Vietnamese Government to reform administrative procedures and foster a favorable business environment. By cutting red tape and leveraging existing digital infrastructure, state agencies can optimize resource allocation. Rather than manually auditing millions of low-value, isolated e-invoices, tax authorities can focus their artificial intelligence and big data analytics tools on higher-risk sectors and complex tax evasion schemes.
Furthermore, reducing compliance overheads for small-scale merchants and household businesses encourages formalization. Many informal online sellers hesitate to register their businesses or formalize their digital storefronts due to the daunting administrative and financial burden of maintaining strict accounting software and e-invoice issuing systems. Streamlining these requirements through platform-level integration could draw a larger segment of the digital economy into the formal tax net.
As the Ministry of Finance finalizes its policy recommendations based on the government’s directives, market stakeholders anticipate clearer regulatory guidelines. If successfully implemented, the transition toward periodic, consolidated e-invoicing for automated e-commerce platforms could serve as a milestone model for digital tax administration in Southeast Asia—proving that regulatory stringency can successfully coexist with administrative efficiency and business agility.